Key Takeaways
- At least 17 countries leave a pension from abroad untaxed. The UAE and the Bahamas have no personal income tax, territorial countries such as Panama, Georgia and the Philippines tax only local income, and Armenia, Montenegro and Hungary exempt pensions by law.
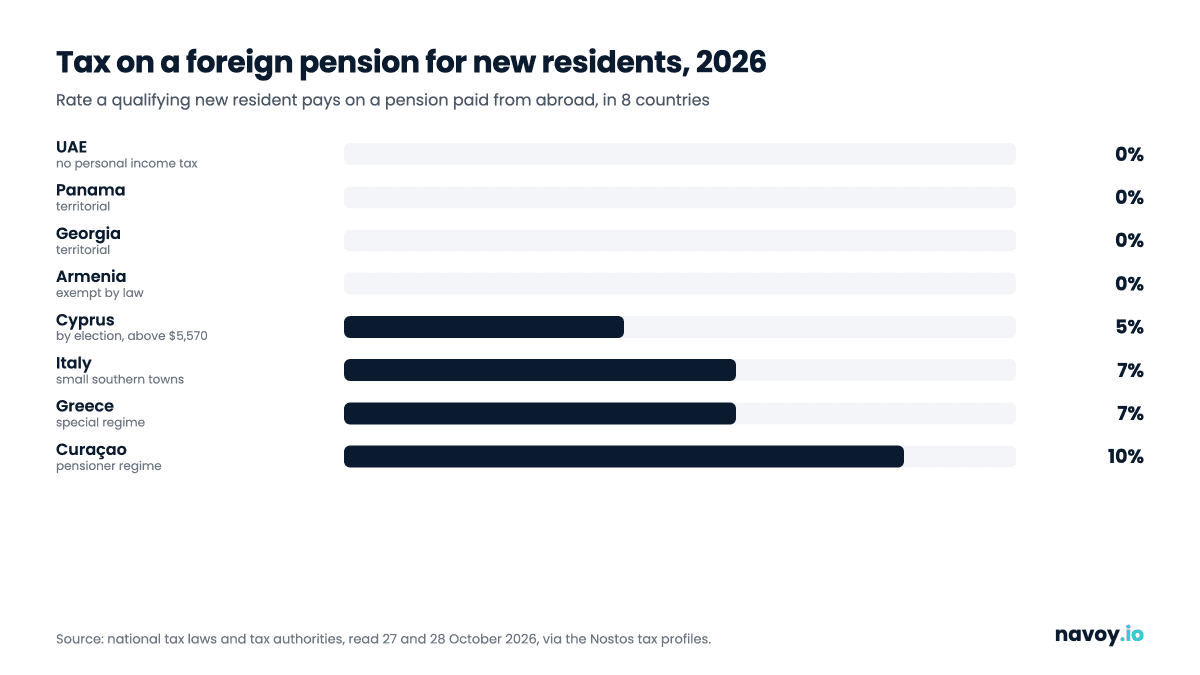
- Italy and Greece tax all foreign income of new pensioner residents at 7%. Italy limits it to towns of up to 30,000 people in eight southern regions, for the year you move and the next nine (10 tax years); Greece has no town limit and runs it for up to 15 years.
- Morocco, Tunisia and Senegal give big pension breaks if you bring the pension in. Morocco and Senegal cut the tax on it by 80%; in Tunisia only 20% of a transferred pension is taxed, and none of it if it was already taxed where it is paid.
- US citizens pay US tax on their pension wherever they live. The foreign earned income exclusion does not apply, because the IRS lists pensions and social security benefits as amounts not included in foreign earned income.
- A UK State Pension is usually not taxed by the UK once you are non-resident, but your new country may tax it. GOV.UK says non-residents do not usually pay UK tax on it, so the rules in the table below decide.
The best countries to retire tax-free on a foreign pension are the ones that do not tax it at all: the UAE and the Bahamas have no personal income tax, territorial countries such as Panama, Costa Rica, Paraguay, Georgia and the Philippines treat a pension paid from abroad as foreign income, and Armenia, Montenegro, Hungary and Bosnia and Herzegovina exempt pensions by law. Next come low flat rates: Cyprus charges 5% above $5,570 (€5,000), and Italy and Greece tax all foreign income of new pensioner residents at 7%. Morocco and Senegal cut the tax on a pension by 80%, and Tunisia taxes only 20% of it, when you transfer the pension into the country.
We built this list from the Nostos tax profiles, one per country for 152 countries, by reading what each says about pensions from abroad and checking it against the tax law or tax authority. Everything is as of October 2026. Rules verified against official sources on 27 and 28 October 2026. This is general information, not tax advice: US citizens are taxed by the US wherever they live, and your home country's exit rules and tax treaty can change the answer, so confirm your case with a qualified adviser before you move.
Which countries don't tax foreign pension income?
The table covers 28 countries where a pension from abroad is untaxed, taxed at a low flat rate, or taxed only in part. Countries where a profile could not confirm the treatment of foreign pensions are left out. "Retiree route" lists a residence path for retirees only where Nostos data names one.
| Country | How a foreign pension is taxed (October 2026) | Retiree route in Nostos data | Nostos page |
|---|---|---|---|
| Not taxed | |||
| UAE | No personal income tax | Not in our data | Dubai |
| Bahamas | No personal income tax | Not in our data | Nassau |
| Armenia | Exempt, foreign pension systems named in the law | Not in our data | Yerevan |
| Belarus | Exempt (Tax Code art. 208) | Not in our data | Minsk |
| Bosnia and Herzegovina | Exempt in both entities; Republika Srpska charges health contributions | Not in our data | Sarajevo |
| Hungary | Exempt; a treaty may let the paying country tax government pensions | Not in our data | Budapest |
| Montenegro | Not counted as income, including from abroad | Not in our data | Kotor |
| Panama | Foreign-source, untaxed even if brought in | Pensionado permit | Panama City |
| Costa Rica | Foreign-source, untaxed | Pensionado or rentista residence | San José |
| Paraguay | Foreign-source, untaxed | Permanent residence; retirees are a solvency category | Asunción |
| Uruguay | Untaxed; foreign investment income pays 12% | Not in our data | Montevideo |
| Georgia | Foreign-source, exempt | Not in our data | Tbilisi |
| Malaysia | Foreign income brought in exempt until 31 Dec 2036 | Not in our data | Penang |
| Philippines | Foreign-source, untaxed for foreigners | SRRV retiree visa | Cebu |
| Kenya | Untaxed unless earned by work in Kenya | Not in our data | Nairobi |
| Belize | Exempt for resident retirees; QRP covers all foreign income | QRP: age 40+, $2,000 a month | San Pedro |
| Dominican Republic | Exempt with pensionado status (Law 171-07); without it, not officially confirmed | Pensionado: $1,500 a month | Santo Domingo |
| Low flat rate | |||
| Cyprus | 5% above $5,570 (€5,000) by election, plus 2.65% GESY | Not in our data | Paphos |
| Italy | 7% on all foreign income in small southern towns, for 10 tax years | 7% regime (see below) | Italy |
| Greece | 7% on all foreign income, up to 15 years | 7% regime (see below) | Chania |
| Curaçao | 10% on foreign income | Penshonado: age 50+, own home | Willemstad |
| Partly taxed | |||
| Tunisia | 20% of a transferred pension taxed; exempt if taxed at source | Not in our data | Tunis |
| Morocco | 0% to 37% after a 70% allowance; tax cut 80% on dirham transfers | Not in our data | Marrakech |
| Senegal | 0% to 43% after a 40% allowance; tax cut 80% if paid into Senegal | Not in our data | Dakar |
| Taxed only when brought in, or later | |||
| Chile | Untaxed for 3 years, then 0% to 40% | Jubilados y rentistas residence | Santiago |
| Mauritius | 0% to 35% on amounts remitted | Premium Visa or EDB retiree permit | Port Louis |
| Malta | Non-doms: 0% to 35% on amounts remitted | Retired pensioner status from 2027 | Valletta |
| Thailand | 0% to 35% when brought in; exempt for LTR Wealthy Pensioners | LTR: age 50+, $80,000 a year | Chiang Mai |
Sources: each country's tax law or tax authority, listed below; Nostos tax profiles and visa guides, read 27 and 28 October 2026.
Shortlisting a base? Plan the trip free with Navoy and compare hotels in Panama City.
Why do some countries not tax a pension from abroad?
No personal income tax
The UAE government states that it does not levy income tax on individuals, and the Bahamas has no personal income tax or capital gains tax. Both raise money through other taxes, such as VAT, so living costs are not tax-free.
Territorial tax: only local income counts
Panama taxes only income produced in Panama (Fiscal Code article 694), so a pension paid from abroad is untaxed whether or not you bring it in. Costa Rica, Georgia and Paraguay work the same way; in Paraguay you become a tax resident only with permanent residence. The Philippines taxes foreigners only on Philippine-source income, and Kenya taxes a foreign pension only in proportion to work done in Kenya. One caution for Costa Rica: a bill published on 30 September 2026 would tax residents' foreign dividends, interest, royalties, rent and capital gains at 15%. Pensions are not on its list, and it is not law yet.
Malaysia taxes residents on foreign income they bring in, but an exemption order covers almost all of it, pensions included, until 31 December 2036. Uruguay's pension tax (IASS) covers only pensions paid by Uruguayan institutions, so a foreign pension is untaxed, while foreign interest, dividends and rent pay 12% from 2026.
The full list of countries that tax only local income is in our guide to territorial tax countries.
Worldwide tax, but pensions exempt
Armenia's Tax Code exempts all pensions and names pensions under foreign systems (article 147). Belarus exempts pensions received under foreign law, Montenegro does not count pensions from abroad as income, and Hungary exempts foreign pensions, though a treaty can still let the paying country tax some, such as government pensions. Bosnia and Herzegovina exempts pensions in both entities, but Republika Srpska charges health contributions on pensions from abroad.
How do Italy's and Greece's 7% pensioner taxes work?
Italy (article 24-ter TUIR). If you receive a pension from a foreign payer, were not an Italian tax resident in the previous five years and move from a country with a tax information-exchange agreement, you can pay 7% on all foreign income instead of progressive rates up to 43% plus surcharges. The catch is the town: since 7 April 2026 it must have no more than 30,000 inhabitants (20,000 before), in Sicily, Calabria, Sardinia, Campania, Basilicata, Abruzzo, Molise or Puglia, or in listed earthquake areas. Palermo, Bari and Lecce are too big. The 7% applies for 10 tax years: the year you move your residence, when the option takes effect, plus the following nine (article 24-ter, paragraphs 4 and 5; the Agenzia delle Entrate's 2020 circular gives a 2019 move running to 2028 inclusive). From 1 January 2027 the same rule sits in article 247 of Italy's new consolidated income tax code (Legislative Decree 117/2026). See the Italy country page for smaller southern bases.
Greece (article 5B). The Greek regime has no town limit. You need a pension from abroad, no Greek tax residence in five of the previous six years, and a move from a country with a tax cooperation agreement with Greece. Apply by 31 March of the year you move, or of the following year. The 7% covers all foreign income for up to 15 years and is paid in one instalment by the end of July, instead of the 9% to 44% scale. Crete is a common choice; see Chania.
Cyprus and Curaçao. Cyprus lets residents choose each year to pay 5% on a foreign pension above $5,570 (€5,000), up from $3,810 (€3,420) before 2026, plus the 2.65% GESY health contribution. Curaçao's penshonado regime taxes foreign income at 10% for people aged 50 or over who lived abroad for 60 consecutive months, own a home worth at least $251,400 (ANG 450,000) and do not work locally.
How do Morocco, Tunisia and Senegal cut the tax on pensions?
All three reward you for moving the money in:
- Morocco: a 70% allowance on the first $17,060 (MAD 168,000) of pension a year (40% above), then the 0% to 37% scale, with the tax on the part transferred definitively in non-convertible dirhams cut by 80% (CGI article 76).
- Tunisia: only 20% of a pension transferred to a Tunisian bank or postal account is taxed, and a pension already taxed in its source country is exempt.
- Senegal: a 40% allowance (at least $3,060 (1,800,000 FCFA)), then an 80% cut in the tax if the pension is paid into a CFA franc account in Senegal. Up to 25% may stay abroad if spent there on you or close family.
Which retiree visas come with a tax exemption?
- Belize QRP. The Belize Tourism Board lists age 40 or over, $2,000 a month ($24,000 a year) from outside Belize and at least 30 consecutive days a year in the country. Holders are exempt from all taxes on income from outside Belize, but may not work locally.
- Dominican Republic, Law 171-07. A foreign pension of at least $1,500 a month qualifies. The pension, and dividends and interest, are then untaxed, though you still file the IR-1 return and each exemption needs approval from the Ministerio de Hacienda.
- Thailand LTR Wealthy Pensioner. Age 50 or over with at least $80,000 a year of pension or passive income (or $40,000 plus a $250,000 Thai investment). Royal Decree 743 exempts the foreign income these holders bring in. Without it, a pension earned while you are resident is taxed when brought into Thailand.
- Chile. Foreigners pay tax only on Chilean income for 3 years after arrival, and the jubilados y rentistas residence is the retiree route.
- Malta and Mauritius. Malta taxes non-domiciled residents, and Mauritius taxes residents, only on foreign income brought in. Mauritius counts a pension you transfer to live on as remitted. From 2027, Malta's retired pensioner status taxes remitted income at 15% with a $16,700 (€15,000) minimum.
Do US citizens pay tax on their pension if they retire abroad?
Yes. The IRS says US citizens abroad are "subject to tax on worldwide income from all sources," so moving abroad does not end US tax on a pension or Social Security. The foreign earned income exclusion does not help either: the IRS lists "pension or annuity payments including social security benefits" among amounts not included in foreign earned income.
What a move changes is the local layer. In a country that does not tax your pension, you pay only US tax. In one that does, a credit for foreign tax on the same income usually keeps you from paying twice, so a low-tax country can cost little more. For the earned-income side, see our guide to digital nomad taxes.
Is a UK State Pension taxed if you retire abroad?
Usually not by the UK. GOV.UK says non-residents "do not usually pay UK tax on" the State Pension, and adds that the country where you live might tax you on your UK income. So the State Pension is treated like any foreign pension in your new country: untaxed in Panama or Georgia, 7% under the Italian or Greek regime, and fully taxed in countries outside this list. Other UK pensions can still be taxed in the UK unless a double taxation agreement gives relief, so check the treaty before you move. If you are leaving the UK for good, our guide to the end of UK non-dom status covers the residence test and the inheritance tax tail.
Which popular retirement countries do tax foreign pensions?
Portugal closed its old non-habitual resident regime, and its replacement, IFICI, leaves foreign pensions taxable, so a pension pays 12.5% to 48% there, plus a solidarity surcharge above $89,040 (€80,000). Spain and France (0% to 45%) also add foreign pensions to their progressive scales, Mexico generally does the same (1.92% to 35%), and Italy and Greece do the same outside the 7% regimes. Moving there can still make sense; just budget for the tax.
How to pick a base once tax is sorted
Tax is one filter. The Nostos city ranker scores cities on cost, safety, internet and climate, and every city page has a "Do you pay tax here on income from abroad?" section built from the same profiles. The full tax profiles are on the Nostos data page. Once you have a shortlist, plan the trip free with Navoy and spend a few weeks in each place before you apply for residence. For Panama, start with hotels in Panama City and flights to Panama City.
Frequently asked questions
Which countries do not tax foreign pension income?
As of October 2026, a pension paid from abroad is not taxed in the UAE and the Bahamas (no personal income tax), in territorial countries such as Panama, Costa Rica, Paraguay, Georgia, the Philippines and Kenya, in Malaysia under an exemption that runs to 31 December 2036, and in Armenia, Belarus, Montenegro, Hungary and Bosnia and Herzegovina, which exempt pensions by law. Uruguay does not tax foreign pensions either, though it taxes foreign investment income at 12%.
Is there a tax-free country to retire for US citizens?
Not fully. The US taxes its citizens on worldwide income from all sources wherever they live, and pensions and social security benefits do not qualify for the foreign earned income exclusion. Retiring in a country that does not tax your pension removes the local tax, so you pay only US tax; in a country that does tax it, a foreign tax credit usually prevents paying twice on the same income.
How does Italy's 7% flat tax for pensioners work?
People who receive a pension from a foreign payer, were not Italian tax residents in the previous five years and move to a town of up to 30,000 inhabitants in Sicily, Calabria, Sardinia, Campania, Basilicata, Abruzzo, Molise or Puglia (or listed earthquake areas) can pay a flat 7% on all foreign income instead of progressive rates of up to 43% plus surcharges, for the tax year of the move and the following nine (10 tax years in total). Italian income is still taxed normally.
Is the Greek 7% pensioner tax open to anyone?
It is open to people who receive a pension from abroad, move their tax residence to Greece, were not Greek tax residents in five of the six previous years and come from a country with a tax cooperation agreement with Greece. You apply by 31 March of the year you move or of the following year, and the 7% covers all foreign income for up to 15 years.
Sources
- Nostos tax profiles (152 countries), Navoy, https://nostos.navoy.io/data, accessed 2026-10-28
- Regime opzionale per i pensionati esteri: che cos'è, Agenzia delle Entrate (Italy), https://www.agenziaentrate.gov.it/portale/schede/agevolazioni/regime-opzionale-per-i-pensionati-esteri-che-cose-cittadini, accessed 2026-10-28
- Circolare n. 21/E del 17 luglio 2020, pensionati esteri nel Mezzogiorno (art. 24-ter TUIR), Agenzia delle Entrate (Italy), https://www.agenziaentrate.gov.it/portale/documents/20143/0/Circolare+n.+21E+del+17.07.2020.pdf/96191701-87ef-ce63-e163-a8a6e37e64ad, accessed 2026-10-27
- Income Tax Code (Law 4172/2013), consolidated to Law 5264/2025, article 5B, Ministry of National Economy and Finance (Greece), https://minfin.gov.gr/wp-content/uploads/2026/04/%CE%9A%CE%A9%CE%94%CE%99%CE%9A%CE%9F%CE%A0%CE%9F%CE%99%CE%97%CE%A3%CE%97-%CE%A4%CE%9F%CE%A5-%CE%9A%CE%A9%CE%94%CE%99%CE%9A%CE%91-%CE%A6%CE%9F%CE%A1%CE%9F%CE%9B%CE%9F%CE%93%CE%99%CE%91%CE%A3-%CE%95%CE%99%CE%A3%CE%9F%CE%94%CE%97%CE%9C%CE%91%CE%A4%CE%9F%CE%A3-%CE%9C%CE%95%CE%A7%CE%A1%CE%99-%CE%A4%CE%9F-%CE%9D-5264-2025.pdf, accessed 2026-10-27
- Tax Incentives, Ministry of Finance (Cyprus), https://www.gov.cy/mof/en/documents/tax-incentives/, accessed 2026-10-27
- Γενικό Σύστημα Υγείας (ΓεΣΥ), Tax Department (Cyprus), https://www.gov.cy/mof-tax/documents/geniko-systima-ygeias-gesy/, accessed 2026-10-27
- Penshonadoregeling, Belastingdienst Curaçao, https://belastingdienst.cw/particulier/themas/penshonadoregeling/, accessed 2026-10-28
- Code Général des Impôts, édition 2021, article 76, Direction Générale des Impôts (Morocco), https://tax.gov.ma/wps/wcm/connect/30b7372b-68d0-462f-b40b-bd5c9f642a26/CGI+2021+version+fran%C3%A7aise.pdf?MOD=AJPERES&CACHEID=ROOTWORKSPACE-30b7372b-68d0-462f-b40b-bd5c9f642a26-nryAoP4, accessed 2026-10-27
- Note Circulaire n° 736, mesures fiscales de la loi de finances 2025, Direction Générale des Impôts (Morocco), https://tax.gov.ma/wps/wcm/connect/7c58c517-850c-4bf7-8f4a-b966b2ee02c1/Note+Circulaire++n%C2%B0+736+relative+aux+mesures+fiscales+de+la+LF+2025.pdf?MOD=AJPERES&CACHEID=ROOTWORKSPACE-7c58c517-850c-4bf7-8f4a-b966b2ee02c1-plIK21O, accessed 2026-10-27
- Aperçu général sur la fiscalité, Ministry of Finance (Tunisia), https://www.finances.gov.tn/fr/apercu-general-sur-la-fiscalite, accessed 2026-10-27
- Code général des impôts du Sénégal, édition janvier 2025, articles 164 and 180, Direction générale des Impôts et des Domaines (Senegal), https://www.dgid.sn/storage/docs/CGI-2025.pdf, accessed 2026-10-27
- Ley 1 de 8 de enero de 2014 (Fiscal Code article 694), Órgano Judicial de Panamá, https://www.organojudicial.gob.pa/uploads/wp_repo/blogs.dir/cendoj/ley-1-de-2014.pdf, accessed 2026-10-27
- Ley 7092, Ley del Impuesto sobre la Renta, SINALEVI (Procuraduría General de la República, Costa Rica), https://sinalevi.go.cr/ResultadosNormativa/Informacion?param1=10969¶m2=148972¶m3=1, accessed 2026-10-27
- Ley N° 6380/2019 de Modernización y Simplificación del Sistema Tributario Nacional, Biblioteca y Archivo del Congreso Nacional (Paraguay), https://www.bacn.gov.py/leyes-paraguayas/9332/ley-n-6380-de-modernizacion-y-simplificacion-del-sistema-tributario-nacional, accessed 2026-10-27
- Preguntas frecuentes, Dirección Nacional de Ingresos Tributarios (Paraguay), https://www.dnit.gov.py/web/portal-institucional/preguntas-frecuentes, accessed 2026-10-27
- Texto Ordenado 2023, Título 12 (IASS), artículo 2, IMPO (Uruguay), https://www.impo.com.uy/bases/todgi2023/101-2024/2_T12, accessed 2026-10-27
- Tax Code of Georgia, consolidated version of 15 October 2026, Legislative Herald of Georgia, https://matsne.gov.ge/en/document/view/1043717, accessed 2026-10-27
- Guidelines: Tax Treatment in Relation to Income Received from Abroad (Amendment), June 2024, Inland Revenue Board of Malaysia, https://www.hasil.gov.my/wp-content/uploads/20240620-guidelines-tax-treatment-in-relation-to-income-received-from-abroad-amendment-june-2024.pdf, accessed 2026-10-27
- Income Tax (Exemption) (No. 5) Order 2022 (Amendment) Order 2024, P.U. (A) 451/2024, Attorney General's Chambers of Malaysia, https://lom.agc.gov.my/ilims/upload/portal/akta/outputp/2584396/PUA%20451_2024.pdf, accessed 2026-10-27
- National Internal Revenue Code of 1997, as amended, sections 23(D) and 42(C), Bureau of Internal Revenue (Philippines), https://www.bir.gov.ph/tax-code, accessed 2026-10-27
- Income Tax Act (Cap. 470), consolidated to 1 July 2026, section 8(1), Kenya Law, https://kenyalaw.org/akn/ke/act/1973/16/eng@2026-07-01, accessed 2026-10-27
- Taxation, u.ae (official portal of the UAE Government), https://u.ae/en/information-and-services/finance-and-investment/taxation, accessed 2026-10-27
- Taxes and Duties, Government of The Bahamas, https://bahamas.gov.bs/taxes-and-duties, accessed 2026-10-28
- Tax Code of the Republic of Armenia, article 147, Armenian Legal Information System (Ministry of Justice), https://www.arlis.am/en/acts/229632, accessed 2026-10-27
- Налоговый кодекс Республики Беларусь (Особенная часть), article 208, pravo.by (Belarus), https://pravo.by/document/?guid=3871&p0=hk0900071, accessed 2026-10-28
- Zakon o porezu na dohodak, Federation of Bosnia and Herzegovina, Federalno ministarstvo finansija, https://www.fmf.gov.ba/Content/Open/102395?n=Zakon_o_porezu_na_dohodak.pdf, accessed 2026-10-27
- Zakon o porezu na dohodak, Republika Srpska, Poreska uprava Republike Srpske, https://www.poreskaupravars.org/dokumenti/zakoni/zakonoporezunadohodak6015.pdf, accessed 2026-10-27
- Zakon o porezu na dohodak fizičkih lica, article 5, Government of Montenegro, https://wapi.gov.me/download/fac4cea9-1dd7-4030-9da6-ba6a59fe8414?version=1.0, accessed 2026-10-27
- Információs füzet 04: Magánszemélyek külföldről származó jövedelme (2026), Nemzeti Adó- és Vámhivatal (Hungary), https://nav.gov.hu/pfile/file?path=/ugyfeliranytu/nezzen-utana/inf_fuz/2026/04.-Maganszemelyek-kulfoldrol-szarmazo-jovedelme-2026.02.20, accessed 2026-10-27
- Retired Persons (Incentives) Act, Chapter 62, Attorney General's Ministry (Belize), https://agm.gov.bz/uploads/laws/63976e60333b3_Cap_62_Retired_Persons__Incentives__Act.pdf, accessed 2026-10-27
- The Qualified Retirement Program, Belize Tourism Board, https://www.belizetourismboard.org/programs-events/retirement-program/, accessed 2026-10-28
- Ley 171-07 sobre Incentivos Especiales a los Pensionados y Rentistas de Fuente Extranjera, Dirección General de Impuestos Internos (Dominican Republic), https://dgii.gov.do/legislacion/leyesTributarias/Documents/Leyes%20de%20Incentivos%20y%20Fomentos/171-07.pdf, accessed 2026-10-27
- Consulta 35 (23 September 2024), exenciones Ley 171-07, Dirección General de Impuestos Internos (Dominican Republic), https://dgii.gov.do/legislacion/consultas/Consultas%20Tecnicas%202024/Septiembre/Consulta%2035-Exenciones%20Ley%20No.171-07.pdf, accessed 2026-10-27
- Revenue Code, Chapter 3 Income Tax, section 41, Revenue Department of Thailand, https://www.rd.go.th/english/37749.html, accessed 2026-10-27
- Royal Decree No. 743 B.E. 2565 (2022), Thailand Board of Investment, https://ltr.boi.go.th/documents/Royal%20Decree%20issued%20under%20the%20Revenue%20Code%20No.743%20(EN).pdf, accessed 2026-10-27
- LTR Visa Thailand: Long-Term Resident Program, Thailand Board of Investment, https://ltr.boi.go.th/, accessed 2026-10-27
- Ley sobre Impuesto a la Renta (DL 824), article 3, Servicio de Impuestos Internos (Chile), https://www.sii.cl/normativa_legislacion/leyimpuestoalarenta.pdf, accessed 2026-10-27
- Residencia Temporal: Jubilados y rentistas, Servicio Nacional de Migraciones (Chile), https://serviciomigraciones.cl/residencia-temporal/subcategorias/jubilados-y-rentistas/, accessed 2026-10-27
- Income Tax Act (Cap. 123), article 4, Laws of Malta, https://legislation.mt/eli/cap/123/eng, accessed 2026-10-27
- Special Schemes, Malta Tax and Customs Administration, https://mtca.gov.mt/personal-tax/individual/special-schemes, accessed 2026-10-27
- Foreign Income, Mauritius Revenue Authority, https://www.mra.mu/index.php/individuals/foreign-income, accessed 2026-10-27
- Income Tax Act 1995, consolidated up to Finance Act 2026, section 5(3), Mauritius Revenue Authority, https://www.mra.mu/download/ITAConsolidated.pdf, accessed 2026-10-27
- Código do IRS, artigo 68.º (Taxas gerais), Portal das Finanças (Portugal), https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/cirs_rep/Pages/irs68.aspx, accessed 2026-10-27
- U.S. citizens and resident aliens abroad, Internal Revenue Service, https://www.irs.gov/individuals/international-taxpayers/us-citizens-and-resident-aliens-abroad, accessed 2026-10-28
- Foreign earned income exclusion: what is foreign earned income?, Internal Revenue Service, https://www.irs.gov/individuals/international-taxpayers/foreign-earned-income-exclusion-what-is-foreign-earned-income, accessed 2026-10-28
- Tax on your UK income if you live abroad, GOV.UK (HM Revenue & Customs), https://www.gov.uk/tax-uk-income-live-abroad, accessed 2026-10-28
- Código do IRS, artigo 16.º (Residência), Portal das Finanças (Portugal), https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/cirs_rep/Pages/irs16.aspx, accessed 2026-10-27
- Ley 35/2006 del IRPF, consolidated text, Boletín Oficial del Estado (Spain), https://www.boe.es/buscar/act.php?id=BOE-A-2006-20764, accessed 2026-10-27
- Imposition des revenus de source étrangère, impots.gouv.fr (DGFiP, France), https://www.impots.gouv.fr/international-particulier/imposition-des-revenus-de-source-etrangere, accessed 2026-10-27
- Impôt sur le revenu 2026 : le barème revalorisé de 0,9 %, Service-Public.fr (France), https://www.service-public.gouv.fr/particuliers/actualites/A18045, accessed 2026-10-27
- Anexo 8 de la Resolución Miscelánea Fiscal para 2026, Servicio de Administración Tributaria (Mexico), https://www.sat.gob.mx/minisitio/NormatividadRMFyRGCE/documentos2026/rmf/anexos/Anexo-8-RMF-2026_DOF-28122025.pdf, accessed 2026-10-27
- Tax on your UK income if you live abroad: pensions, GOV.UK (HM Revenue & Customs), https://www.gov.uk/tax-uk-income-live-abroad/pensions, accessed 2026-10-28
- Testo unico delle imposte sui redditi (DPR 917/1986), articolo 24-ter, text in force 7 April to 31 December 2026, Normattiva (Italy), https://www.normattiva.it/uri-res/N2Ls?urn:nir:presidente.repubblica:decreto:1986-12-22;917~art24ter, accessed 2026-10-28
- Decreto legislativo 19 giugno 2026, n. 117, Testo unico delle disposizioni legislative in materia di imposte sui redditi, articolo 247, Normattiva (Italy), https://www.normattiva.it/uri-res/N2Ls?urn:nir:stato:decreto.legislativo:2026-06-19;117, accessed 2026-10-28
- Migraciones actualiza el régimen de acreditación de solvencia económica para extranjeros, Dirección Nacional de Migraciones (Paraguay), https://migraciones.gov.py/migraciones-actualiza-el-regimen-de-acreditacion-de-solvencia-economica-para-extranjeros/, accessed 2026-10-27
- Nostos visa guides (residence routes for retirees in Panama, Costa Rica, Paraguay, the Philippines and Mauritius), Navoy, https://nostos.navoy.io/visas, accessed 2026-10-28
About the Author
Ranym Garali
Ranym is the Marketing and Content Lead at Navoy. She's been writing about travel for two years and digs into the data behind each piece, flight prices, visa rules and what people are actually searching for , so the advice holds up in practice.