Key Takeaways
- 34 countries tax individuals on a territorial basis in 2026. Of 152 countries in the Nostos tax data, 34 tax residents only on local-source income, 101 tax worldwide income, 8 use a remittance basis and 9 have no personal income tax.
- Territorial rarely helps remote workers. In 32 of the 34, pay for work you do while in the country is local income even with a foreign employer; only Angola (in 2026) and Seychelles (for salaries, in practice) leave it alone.
- Passive income is where territorial countries pay off. In 27 of them, foreign dividends, interest, capital gains and rent are largely untaxed for residents, including Panama, Georgia, Malaysia and Paraguay.
- Seven territorial countries still tax some foreign investment income. Angola, the Dominican Republic, Egypt, Lebanon, Uruguay, Zambia and Zimbabwe tax certain foreign dividends or interest.
- Eight countries tax foreign income only when you bring it in. Barbados, Guyana, Ireland, Jamaica, Malta, Mauritius, Thailand and Trinidad and Tobago, mostly for residents not domiciled there.
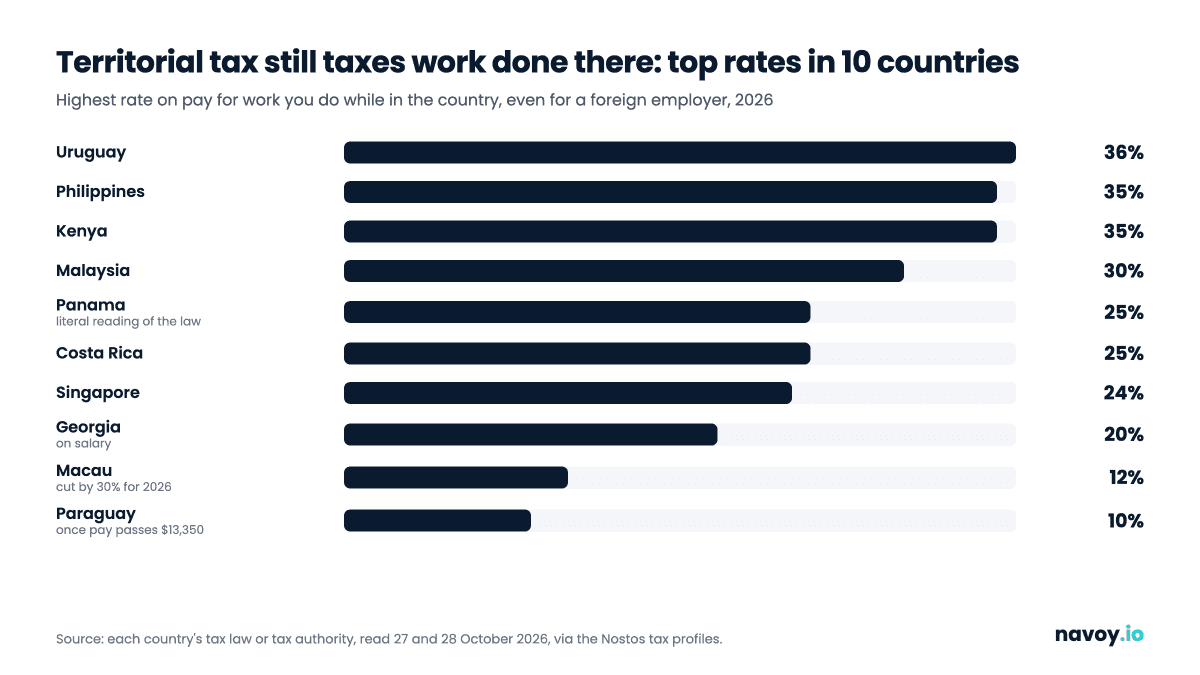
Territorial tax countries tax residents only on income that comes from inside the country, so dividends, interest, rent and pensions from abroad usually go untaxed. Of the 152 countries in the Nostos tax data, 34 use a territorial system for individuals, from Panama and Costa Rica to Georgia, Malaysia and Singapore, and 8 more tax foreign income only when you bring it in. The catch: in 32 of the 34, pay for work you do while living there counts as local income, even when your employer or clients are abroad.
Everything below is as of October 2026 and comes from each country's tax law or tax authority, collected in Nostos, Navoy's free city chooser for nomads. Rules verified against official sources on 27 and 28 October 2026. It is general information, not tax advice. If you are a US citizen, you are taxed on worldwide income wherever you live, and your home country's own exit rules can keep you resident there, so check both before you move.
What is a territorial tax system?
A territorial system taxes income by where it comes from, not by where you live. A worldwide system taxes residents on everything they earn, wherever it arises. A remittance system sits in between: foreign income is taxed only when you bring it into the country.
Across the 152 countries in Nostos, 101 tax residents on worldwide income, 34 are territorial, 8 use a remittance basis for at least some newcomers and 9 levy no personal income tax. "Territorial" is a label, not a promise. Some territorial countries still tax certain foreign investment income, and almost all of them tax work done on their soil. The tables below show which is which.
Scouting a base first? Plan the trip free with Navoy and compare hotels in Panama City.
Which countries are territorial tax countries in 2026?
The tables below list the 34 territorial countries in Nostos, by region, A to Z. "Exempt" means a resident pays no income tax there on that foreign income. "Work done there" is the rate on pay for work you do while in the country, even for a foreign employer. Each city link opens a Nostos page with the tax section.
Territorial tax countries in Latin America
| Country | Foreign investment income | Foreign pension | Work done there | Note | City |
|---|---|---|---|---|---|
| Belize | Exempt | Exempt | Employees 25%; freelancers 6% of gross fees | Retirement program members pay nothing on foreign income | San Pedro |
| Bolivia | Exempt | Exempt | 13% | Wealth tax of 1.4% to 2.4% above $2.5 million (Bs30 million) | La Paz |
| Costa Rica | Exempt | Exempt | 0% to 25% | Nomad permit holders exempt; a bill would tax foreign investment income at 15% | San José |
| Dominican Republic | Taxed 0% to 25% from the third year | Not named in the law | 0% to 25% | Pensioner and rentista residents exempt | Santo Domingo |
| El Salvador | Exempt since 2024 | Exempt | Likely 0% to 30% | 30% flat if not domiciled | San Salvador |
| Guatemala | Exempt | Exempt | 5% to 7% | Inheritance tax abolished in April 2026 | Antigua |
| Honduras | Exempt, though an older law conflicts | Exempt | 0% to 25% | Resident after about 90 days in a year | Roatán |
| Nicaragua | Exempt unless the capital is Nicaraguan | Exempt | 0% to 30% | Social security pensions exempt in any case | Granada |
| Panama | Exempt | Exempt | 0% to 25% on a literal reading | No official ruling for remote workers | Panama City |
| Paraguay | Exempt | Exempt | 8% to 10% once pay passes $13,350 (G 80 million) a year | Tax resident only with permanent residence | Asunción |
| Uruguay | Taxed 12% | Exempt | 0% to 36% | Newcomers can opt out of the 12% for 11 years | Montevideo |
Territorial tax countries in Asia
| Country | Foreign investment income | Foreign pension | Work done there | Note | City |
|---|---|---|---|---|---|
| Bhutan | Exempt | Exempt | 0% to 30% | A resident's business income is taxed wherever it arises | Thimphu |
| Hong Kong | Exempt | Unclear | 2% to 17%, capped at a 15%/16% standard rate | Ask the IRD about a foreign pension | Hong Kong |
| Macau | Exempt | Exempt | 7% to 12%, cut by 30% for 2026 | Work tax starts above $17,820 (MOP 144,000) | Macau |
| Malaysia | Exempt to 31 December 2036 | Exempt to 2036 | 0% to 30%; 30% flat if non-resident | The exemption is time-limited | Kuala Lumpur |
| Maldives | Exempt | Exempt | 0% to 15% | 0% up to $46,620 (MVR 720,000) a year | Malé |
| Philippines | Exempt for foreigners | Exempt for foreigners | 25% of gross, or 0% to 35% after 180 days | Freelancers can choose 8% of receipts | Manila |
| Singapore | Exempt, even if brought in | Exempt | 0% to 24%; at least 15% if non-resident | Applies to foreign employers too | Singapore |
| Taiwan | Outside regular tax | Exempt | 18% after 90 days; 5% to 40% from 183 days | 20% minimum tax above $231,400 (NT$7.5 million) of basic income | Taipei |
Territorial tax countries in Europe and the Caucasus
| Country | Foreign investment income | Foreign pension | Work done there | Note | City |
|---|---|---|---|---|---|
| Georgia | Exempt | Exempt | 20% on salary; 1% of turnover for small businesses | The 1% status excludes consulting | Tbilisi |
| Moldova | Exempt for foreign residents | Not confirmed | 12% above $1,650 (MDL 29,700) | Moldovan dividends pay 6% | Chișinău |
Territorial tax countries in the Middle East and North Africa
| Country | Foreign investment income | Foreign pension | Work done there | Note | City |
|---|---|---|---|---|---|
| Egypt | Dividends taxed 0% to 27.5%; interest, rent exempt | Exempt | 0% to 27.5% | Gains on shares not listed in Egypt taxed too | Cairo |
| Iran | Exempt for foreign nationals | Exempt | 10% to 30% (unconfirmed) | Iranian citizens are taxed worldwide | Tehran |
| Iraq | Exempt for foreigners | Exempt | Likely 3% to 15% | Iraqi citizens are taxed worldwide | Erbil |
| Jordan | Exempt unless the money came from Jordan | Exempt | Likely 5% to 30% | Money from Jordan pays 10% | Amman |
| Lebanon | Dividends and interest 10% | Not confirmed | 2% to 25% | Inheritance tax applies | Beirut |
| Syria | Mostly exempt | Exempt | Taxable; rates unconfirmed | Official sites were unreachable | Damascus |
Territorial tax countries in Africa
| Country | Foreign investment income | Foreign pension | Work done there | Note | City |
|---|---|---|---|---|---|
| Angola | Dividends, interest, share gains 10% | Exempt | Not taxed in 2026 if paid from abroad | A new code is expected to tax residents from 2027 | Luanda |
| Kenya | Exempt | Exempt if earned abroad | 10% to 35%, even for work done abroad | Renting a home can make you resident on arrival | Nairobi |
| Malawi | Exempt | Exempt if earned abroad | Up to 40% on salary | Other income 30% above K2,040,000 | Lilongwe |
| Namibia | Mostly exempt | Mostly exempt | 18% to 37% above $6,010 (N$100,000) | Foreign interest exempt only on savings from abroad | Windhoek |
| Seychelles | Exempt | Exempt | Foreign salary untaxed in practice; freelancers 1.5% of turnover | The salary point is not settled in law | Victoria |
| Zambia | Interest and dividends 0% to 37% | Exempt if earned abroad | 0% to 37% | Foreign rent and gains exempt | Lusaka |
| Zimbabwe | Dividends 20%, interest 25% | Mostly exempt | 0% to 40% plus a 3% AIDS levy on the tax | Foreign rent and gains exempt | Harare |
Sources: each country's tax law or tax authority, read between 27 and 28 October 2026, via the Nostos open data. Rates are the range on wages or fees; "likely" marks a rule the law implies but no official guidance confirms.
Does a territorial tax system cover remote work?
Usually not, and this is the part most "tax-free countries" lists skip. Territorial systems decide the source of work income by where you do the work, not by where the payer is. If you open your laptop in Panama City, the work happens in Panama.
Only 2 of the 34 territorial countries leave remote pay alone, and both with caveats. Angola's 2026 work-income tax reaches only services provided to people or businesses based in Angola, but Parliament approved a new personal income tax code on 25 June 2026 meant to replace it from 2027, and no final text had appeared in an official source by late October. Seychelles collects salary tax only through employers there, so pay from a foreign employer is untaxed in practice, though the law does not say so outright, and freelancers on the islands owe business tax.
Everywhere else on the list, remote pay is local income:
- Panama taxes only income produced in Panama, but its tax regulations treat services performed in Panama as Panamanian-source whoever pays. The rates are 0% up to $11,000 (B/.11,000), 15% to $50,000 (B/.50,000) and 25% above. No official ruling settles this for remote workers, so treat it as a grey area. The Panama visa guide covers the remote worker visa, which grants no tax exemption.
- Costa Rica defines Costa Rican-source income as services rendered in the country, whoever the parties are. Remote work is taxed at 0% to 25% unless you hold the digital nomad permit under Law 10008, which exempts it; see the Costa Rica visa guide.
- Georgia is territorial: its Tax Code exempts a resident's income that is not from a Georgian source and taxes personal income at 20%. Work done in Georgia is Georgian-source, though, so a foreign salary pays 20%. Registered freelancers can usually pay 1% of turnover instead. The Georgia visa guide covers the one-year visa-free stay.
- Malaysia exempts foreign income that residents bring in until 31 December 2036, but its tax authority says pay for work done in Malaysia is taxable even when paid from abroad. The Malaysia visa guide covers the DE Rantau nomad pass.
- Singapore's tax authority says overseas income received by individuals is generally not taxable, with one exception that matters here: income from working in Singapore for a foreign employer.
Kenya goes further than the rest: it taxes a resident's pay wherever the work is done. This matches the wider data. In 140 of the 152 countries in Nostos, pay for remote work done while you are physically there is taxable, even when the employer or clients are abroad. That is why "territorial" helps passive income far more than it helps remote workers. For how nomad visas and the 183-day rule interact, read which digital nomad visas make you pay tax.
Which territorial countries still tax foreign investment income?
Seven of the 34 tax some foreign investment income:
- Angola: 10% on dividends, interest and share gains.
- Dominican Republic: foreign dividends, interest and financial gains join the 0% to 25% scale from the third year of residency.
- Egypt: foreign dividends and gains on shares not listed in Egypt, at 0% to 27.5%.
- Lebanon: a flat 10% on a resident's foreign dividends and interest.
- Uruguay: 12% on foreign interest and dividends, and from 2026 on foreign rent and gains too, unless a newcomer opts into the 11-year regime.
- Zambia and Zimbabwe: foreign interest and dividends, but not foreign rent or gains.
The other 27 leave foreign dividends, interest, gains and rent largely untaxed, with the narrow exceptions noted in the tables. Watch Costa Rica: bill 25.796, published on 30 September 2026, would tax residents' foreign passive income at 15%, but it is not law.
Which countries tax foreign income only when you bring it in?
Eight countries use a remittance basis: foreign income is taxed only if you bring it into the country. In six of them it applies only to residents who are not domiciled there, which covers most foreign newcomers. In all eight, pay for work done in the country is taxed as local income, unless a special status such as Barbados's Welcome Stamp or Mauritius's Premium Visa applies.
| Country | Who gets the remittance basis | Work done there | Note | City |
|---|---|---|---|---|
| Barbados | Residents not domiciled | 11.5% to 27.5% | Welcome Stamp holders pay no Barbados income tax | Bridgetown |
| Guyana | Residents not domiciled | 25% to 35% | Allowance of $8,020 (G$1,680,000) in 2026 | Georgetown |
| Ireland | Residents not domiciled | Up to 52.35% with USC and PRSI | Resident after 183 days, or 280 over two years | Dublin |
| Jamaica | Residents not domiciled | 25% to 30% | 30% applies above $37,810 (J$6 million) a year | Kingston |
| Malta | Residents not domiciled | 0% to 35% | Foreign capital gains untaxed even if brought in | Valletta |
| Mauritius | All residents | 0% to 35% | Premium Visa remote pay taxed only if remitted | Port Louis |
| Thailand | Residents, on income earned from 2024 | 0% to 35% | Savings earned before 2024 can come in tax-free | Chiang Mai |
| Trinidad and Tobago | Residents not domiciled | 25% to 30% | Domiciled residents are taxed on worldwide income | Port of Spain |
Two details matter here. Malta charges ordinarily resident non-doms at least $5,570 (€5,000) a year if they have $38,960 (€35,000) or more of foreign income and do not bring it all in. Thailand applies its rule to residents who stay 180 days or more in a calendar year, and you must be able to show which year a transfer was earned in.
Who benefits most from a territorial tax country?
The clearest winners live on income not tied to where they sit: retirees with foreign pensions, investors and landlords with property abroad. In Panama, Georgia, Malaysia or Paraguay, that income is untaxed even after you become resident.
Remote workers gain much less. In most territorial countries, pay for work you do there is taxed like a local's, often whether or not you have become tax resident. Nomad regimes such as Costa Rica's permit are exceptions to the territorial rule, not part of it.
Two more limits apply to everyone. Becoming resident in a territorial country does not automatically end your residence at home, and US citizens owe US tax on worldwide income wherever they live. A territorial country can lower what you pay locally; it cannot switch off what your home country claims.
How to use this list to choose a base
Start with the kind of income you have. Passive income points to the 27 countries with no tax on foreign investment income; a salary means comparing the "Work done there" rates instead. Then compare cities: the Nostos ranker scores 1,000 cities on cost, safety, internet and climate, and every city page has the "Do you pay tax here on income from abroad?" section with sources. When you have a shortlist, plan the trip free with Navoy, then check hotels in Panama City and flights to Panama City.
Frequently asked questions
Which countries do not tax foreign income?
As of October 2026, 34 countries tax residents only on income from inside the country, including Panama, Costa Rica, Paraguay, Georgia, Malaysia, Singapore and Hong Kong. In 27 of them, foreign dividends, interest, capital gains and rent are largely untaxed for residents. Eight more, such as Thailand and Malta, tax foreign income only when you bring it into the country. Most of these countries still tax pay for work you do while living there.
Is Georgia a territorial tax country?
Yes. Georgia's Tax Code exempts a resident's income that is not from a Georgian source, so foreign dividends, interest, rent, gains and pensions are untaxed. Work you do while in Georgia is Georgian-source even for a foreign employer: a salary pays the flat 20% income tax, while registered freelancers with Small Business Status usually pay 1% of turnover, a status not open to consulting.
Do remote workers pay tax in Panama?
Probably, on a literal reading of the law. Panama taxes only income produced in Panama, but its tax regulations treat services performed in Panama as Panamanian-source whoever pays, which would put remote pay on the 0% to 25% scale. No official ruling settles the question for remote workers, so get written advice from a Panamanian adviser. Foreign investment income and pensions are untaxed either way.
Is Thailand a territorial tax country?
Not exactly. Thailand uses a remittance basis: foreign income earned from 1 January 2024, in a calendar year when you spent 180 days or more there, is taxed at 0% to 35% when you bring it into Thailand. Money left abroad, or earned before 2024, is not taxed. Pay for work done while you are in Thailand is Thai income whether or not you remit it.
Sources
- Lei n.º 18/14, de 22 de Outubro: Código do Imposto sobre os Rendimentos do Trabalho (Diário da República, I Série, n.º 192), Administração Geral Tributária (AGT), https://www.ucm.minfin.gov.ao/cs/groups/public/documents/document/aw4x/mjm3/~edisp/minfin1237856.pdf, accessed 2026-10-28
- Decreto Legislativo Presidencial n.º 2/14, de 20 de Outubro: Código do Imposto sobre a Aplicação de Capitais, Administração Geral Tributária (AGT), https://www.ucm.minfin.gov.ao/cs/groups/public/documents/document/aw4y/njky/~edisp/minfin2692995.pdf, accessed 2026-10-28
- Resenha legislativa referente ao mês de Dezembro de 2025, Ministério das Finanças de Angola (Gabinete Jurídico), https://cms.minfin.gov.ao/api/assets/portal-minfin/6ef7b2cc-bde1-426f-b96b-6d9e9d1f8f71/, accessed 2026-10-28
- Assembleia Nacional aprova Proposta de Lei do Código do IRPS, Ministério das Finanças de Angola, https://www.minfin.gov.ao/sala-de-imprensa/noticias/noticia/assembleia-nacional-aprova-proposta-de-lei-do-codigo-do-irps, accessed 2026-10-28
- Individuals, Barbados Revenue Authority, https://www.bra.gov.bb/Individuals, accessed 2026-10-28
- Barbados Welcome Stamp, Visit Barbados (Barbados Tourism Marketing Inc.), https://www.visitbarbados.org/barbados-welcome-stamp, accessed 2026-10-28
- Ley N° 843 y Decretos Reglamentarios, texto ordenado, complementado y actualizado al 30/09/2026, Servicio de Impuestos Nacionales (SIN), https://www.impuestos.gob.bo/wp-content/uploads/2026/10/1.-LEY-N%C2%B0-843-09-26-1.pdf, accessed 2026-10-27
- Ley N° 1357 de 28 de diciembre de 2020, Impuesto a las Grandes Fortunas (IGF), Servicio de Impuestos Nacionales (SIN), https://www.impuestos.gob.bo/wp-content/uploads/2025/11/LEY1357.pdf, accessed 2026-10-27
- Income Tax Act of Bhutan 2025, Department of Revenue and Customs, Ministry of Finance (drc.gov.bt), https://www.drc.gov.bt/wp-content/uploads/2025/09/Income-Tax-Act-of-Bhutan-2025.pdf, accessed 2026-10-27
- Income and Business Tax Act, Chapter 55, Revised Edition 2020, Attorney General's Ministry, Government of Belize, https://agm.gov.bz/uploads/laws/63976e6032352_Cap_55_Income_and_Business_Tax_Act.pdf, accessed 2026-10-27
- Income and Business Tax (Amendment) Act, 2024 (Act No. 40 of 2024), Belize Tax Service, https://media.bts.gov.bz/uploads/Act_No_40_of_2024_Income_and_Business_Tax_Amendment_Act_2024_b6bf496b66.pdf, accessed 2026-10-27
- Ley 7092, Ley del Impuesto sobre la Renta (consolidated text, version 83 of 83), SINALEVI, Sistema Nacional de Legislación Vigente, Procuraduría General de la República, https://sinalevi.go.cr/ResultadosNormativa/Informacion?param1=10969¶m2=148972¶m3=1, accessed 2026-10-27
- Ley 10008, Ley para atraer trabajadores y prestadores remotos de servicios de carácter internacional, SINALEVI, Sistema Nacional de Legislación Vigente, Procuraduría General de la República, https://sinalevi.go.cr/ResultadosNormativa/Informacion?param1=95085¶m2=129850¶m3=1, accessed 2026-10-27
- Proyecto de ley expediente 25.796, Ley sobre el gravamen de rentas pasivas de fuente extranjera (Alcance 130 to La Gaceta, 30 September 2026), Imprenta Nacional de Costa Rica (La Gaceta), https://www.imprentanacional.go.cr/pub/2026/09/30/ALCA130_30_09_2026.pdf, accessed 2026-10-27
- Código Tributario de la República Dominicana (Ley 11-92), consolidated text, Dirección General de Impuestos Internos (DGII), https://dgii.gov.do/transparencia/baseLegal/Documents/Leyes/11-92.pdf, accessed 2026-10-27
- Aviso 22-25: criterio de territorialidad de las rentas de personas físicas residentes, Dirección General de Impuestos Internos (DGII), https://dgii.gov.do/publicacionesOficiales/avisosInformativos/Documents/2025/22-25.pdf, accessed 2026-10-27
- Comunidad de Ayuda DGII: Extranjero trabajando remoto (official solution), Dirección General de Impuestos Internos (DGII), Comunidad de Ayuda, https://ayuda.dgii.gov.do/conversations/discusiones/extranjero-trabajando-remoto/6425b1f0c7dea832a77ceb44, accessed 2026-10-27
- Law No 91 of 2005 promulgating the Income Tax Law (Official Gazette No 23 (cont.), 9 June 2005), Egyptian Tax Authority (eta.gov.eg), scan of the Official Gazette, https://eta.gov.eg/sites/default/files/2024-03/law_no.91-2005.pdf, accessed 2026-10-27
- Law No 30 of 2023 amending the Income Tax Law, Egyptian Tax Authority (eta.gov.eg), scan of the Official Gazette, https://eta.gov.eg/sites/default/files/2024-03/law_no.30-2023.pdf, accessed 2026-10-27
- Law No 7 of 2024 amending the Income Tax Law (Official Gazette No 7 bis (A), 21 February 2024), Egyptian Tax Authority (eta.gov.eg), scan of the Official Gazette, https://eta.gov.eg/sites/default/files/2024-03/law_no.7-2024.pdf, accessed 2026-10-27
- Tax Code of Georgia (consolidated version of 15 October 2026), Legislative Herald of Georgia (matsne.gov.ge), https://matsne.gov.ge/en/document/view/1043717, accessed 2026-10-27
- Decreto 10-2012, Ley de Actualización Tributaria (consolidated text, SAT version of 26 October 2026), Superintendencia de Administración Tributaria (SAT), https://portal.sat.gob.gt/portal/descarga/1899/legislacion-tributaria/97573/decreto-numero-10-2012-ley-de-actualizacion-tributaria-2, accessed 2026-10-27
- Income Tax Act, Chapter 81:01 (consolidated, October 2020), Guyana Revenue Authority, https://www.gra.gov.gy/storage/2020/10/Income-Tax-Act-October-21-2020.pdf, accessed 2026-10-28
- Notice to Employers, Employees & Self-Employed Persons: Revised Personal Allowance and Deductions for Income Tax 2026 (26 February 2026), Guyana Revenue Authority, https://gra.gov.gy/notice-to-employers-employees-self-employed-persons-revised-personal-allowance-and-deductions-for-income-tax-2026/, accessed 2026-10-28
- A guide to Salaries Tax for people coming to work in Hong Kong (PAM 42(e), April 2026), Inland Revenue Department (ird.gov.hk), https://www.ird.gov.hk/eng/pdf/pam42e.pdf, accessed 2026-10-28
- Tax Rates of Salaries Tax & Personal Assessment, GovHK (gov.hk), https://www.gov.hk/en/residents/taxes/taxfiling/taxrates/salariesrates.htm, accessed 2026-10-28
- Prevailing Tax Policy, Financial Services and the Treasury Bureau (fstb.gov.hk), https://www.fstb.gov.hk/en/treasury/general/prevailing-tax-policy.htm, accessed 2026-10-28
- Chargeable and Non-chargeable Income (Salaries Tax), GovHK (gov.hk), https://www.gov.hk/en/residents/taxes/salaries/salariestax/chargeable/index.htm, accessed 2026-10-28
- Ley del Impuesto sobre la Renta, Decreto-Ley 25 (consolidated text up to Acuerdo SAR-07-2025), Servicio de Administración de Rentas (SAR), https://www.sar.gob.hn/download/texto-consolidado-decreto-ley-numero-25-ley-del-impuesto-sobre-la-renta/, accessed 2026-10-27
- Código Tributario, Decreto 170-2016 (updated text up to Decreto 180-2020), Servicio de Administración de Rentas (SAR), https://www.sar.gob.hn/download/texto-actualizado-codigo-tributario-decreto-170-2016-hasta-el-decreto-180-2020-preparado-por-el-departamento-de-asesoria-y-procuracion-legal-de-la-dnj/, accessed 2026-10-27
- What is domicile and the domicile levy?, Revenue (Office of the Revenue Commissioners), https://www.revenue.ie/en/jobs-and-pensions/tax-residence/domicile-domicile-levy.aspx, accessed 2026-10-27
- How to know if you are resident for tax purposes, Revenue (Office of the Revenue Commissioners), https://www.revenue.ie/en/jobs-and-pensions/tax-residence/resident-for-tax-purposes.aspx, accessed 2026-10-27
- Income Tax Law No 113 of 1982 and its amendments (consolidated Arabic text), General Commission of Taxes, Ministry of Finance (tax.mof.gov.iq), https://tax.mof.gov.iq/%D9%82%D8%A7%D9%86%D9%88%D9%86-%D8%B6%D8%B1%D9%8A%D8%A8%D8%A9-%D8%A7%D9%84%D8%AF%D8%AE%D9%84-%D8%B1%D9%82%D9%85-113-%D9%84%D8%B3%D9%86%D8%A9-1982-%D9%88%D8%AA%D8%B9%D8%AF%D9%8A%D9%84%D8%A7%D8%AA%D9%87/, accessed 2026-10-27
- Direct Taxation Act of 1366 (1988) with later amendments, consolidated, National Laws and Regulations Portal of the Islamic Republic of Iran (qavanin.ir), https://qavanin.ir/Law/TreeText/?IDS=892583840653829785, accessed 2026-10-27
- The Income Tax Act (Revised Laws of Jamaica, consolidated), Legal Information Portal of Jamaica (lipj.gov.jm), Government of Jamaica, https://lipj.gov.jm/cms/uploads/The_Income_Tax_Act_2017_compressed_1_e5d8740852.pdf, accessed 2026-10-27
- Individual Income Tax Rates, Threshold and Exemptions 2013 to 2028, Tax Administration Jamaica, https://www.jamaicatax.gov.jm/documents/10194/15307403/INDIVIDUAL_INCOME_TAX_RATES_THRESHOLD_AND_EXEMPTIONS_2013-2028.pdf/c0987986-f35c-7106-85a4-d488a6f52627, accessed 2026-10-27
- Income Tax Law No 34 of 2014 and its amendments (consolidated Arabic text), Income and Sales Tax Department, Ministry of Finance (istd.gov.jo), https://www.istd.gov.jo/EBV4.0/Root_Storage/AR/EB_Tenders/%D9%82%D8%A7%D9%86%D9%88%D9%86_%D8%B6%D8%B1%D9%8A%D8%A8%D8%A9_%D8%A7%D9%84%D8%AF%D8%AE%D9%84_34_%D9%84%D8%B3%D9%86%D8%A9_2014_%D9%88%D8%AA%D8%B9%D8%AF%D9%8A%D9%84%D8%A7%D8%AA%D9%87.docx, accessed 2026-10-27
- Income Tax Act (Cap. 470), consolidated to 1 July 2026, Kenya Law, National Council for Law Reporting, https://kenyalaw.org/akn/ke/act/1973/16/eng@2026-07-01, accessed 2026-10-27
- Income Tax Law, Legislative Decree No 144 of 12/06/1959 (consolidated Arabic text), Ministry of Finance, Lebanon (finance.gov.lb), https://www.finance.gov.lb/en-us/Taxation/LRT/Documents/%D9%82%D8%A7%D9%86%D9%88%D9%86%20%D8%B6%D8%B1%D9%8A%D8%A8%D8%A9%20%D8%A7%D9%84%D8%AF%D8%AE%D9%84.pdf, accessed 2026-10-27
- Tax on income from movable capital (Schedule III): laws and decisions, Ministry of Finance, Lebanon (finance.gov.lb), https://www.finance.gov.lb/en-us/Taxation/LRT/CGT/Pages/default.aspx, accessed 2026-10-27
- Tax Code of the Republic of Moldova No 1163/1997 (Codul fiscal), State Register of Legal Acts (legis.md), Ministry of Justice, https://www.legis.md/cautare/downloadpdf/79283, accessed 2026-10-28
- Professional Tax Regulation (Regulamento do Imposto Profissional), full republication by Chief Executive Order No 267/2003, Official Gazette of the Macao SAR (Boletim Oficial, bo.dsaj.gov.mo), https://bo.dsaj.gov.mo/bo/i/2003/48/despce267.asp, accessed 2026-10-28
- Income Tax Act (Cap. 123), consolidated to 10 March 2026, Laws of Malta, legislation.mt, https://legislation.mt/eli/cap/123/eng, accessed 2026-10-27
- Tax Residence, Malta Tax and Customs Administration (MTCA), https://mtca.gov.mt/personal-tax/individual/tax-residence, accessed 2026-10-27
- Income Tax Act 1995 (consolidated up to Finance Act 2026), Mauritius Revenue Authority (mra.mu), https://www.mra.mu/download/ITAConsolidated.pdf, accessed 2026-10-27
- FAQs: Premium Visa (October 2022), Mauritius Revenue Authority (mra.mu), https://www.mra.mu/download/FAQsPremiumVISA.pdf, accessed 2026-10-27
- Foreign Income, Mauritius Revenue Authority (mra.mu), https://www.mra.mu/index.php/individuals/foreign-income, accessed 2026-10-27
- Income Tax Act (Law Number 25/2019), consolidated unofficial English translation, Maldives Inland Revenue Authority (mira.gov.mv), https://mira.gov.mv/Legislations/View/Incometaxact, accessed 2026-10-28
- Taxation Act (Cap. 41:01), Revenue Appeals Tribunal of Malawi (RAT eLibrary), https://elibrary.rat.gov.mw/items/cf53533b-6965-4152-aca7-9641a4b926d9, accessed 2026-10-28
- Public Notice: New Tax Measures (Taxation (Amendment) and Value Added Tax (Amendment) (No. 2) Acts 2025), Malawi Revenue Authority, https://www.mra.mw/admin/storage/download_files/1767952247_NEW%20TAX%20MEASURES...pdf, accessed 2026-10-28
- Income Tax (Exemption) (No. 5) Order 2022 [P.U. (A) 234/2022], Attorney General's Chambers of Malaysia, Laws of Malaysia Online (lom.agc.gov.my), https://lom.agc.gov.my/ilims/upload/portal/akta/outputp/1737434/PUA234.pdf, accessed 2026-10-27
- Income Tax (Exemption) (No. 5) Order 2022 (Amendment) Order 2024 [P.U. (A) 451/2024], Attorney General's Chambers of Malaysia, Laws of Malaysia Online (lom.agc.gov.my), https://lom.agc.gov.my/ilims/upload/portal/akta/outputp/2584396/PUA%20451_2024.pdf, accessed 2026-10-27
- Tax Treatment: Residents & Non-Residents (update 08/04/2026), Inland Revenue Board of Malaysia (LHDN, hasil.gov.my), https://www.hasil.gov.my/wp-content/uploads/Tax-Treatment-Residents-Non-Residents.pdf, accessed 2026-10-27
- Income Tax Act 24 of 1981 (consolidated as at 16 September 2024), Namibia Revenue Agency (namra.org.na), https://www.namra.org.na/documents/cms/uploaded/income-tax-act-24-of-1981-debf9c72ad.pdf, accessed 2026-10-27
- Ley 822, Ley de Concertación Tributaria (La Gaceta No. 241 of 17 December 2012), Dirección General de Ingresos (DGI), copy of La Gaceta, Diario Oficial, https://www.dgi.gob.ni/pdfLegislacion/58, accessed 2026-10-27
- Ley 1 de 8 de enero de 2014 (restores Article 694 of the Fiscal Code), Gaceta Oficial 27450-A, Órgano Judicial de Panamá (CENDOJ), copy of the Gaceta Oficial, https://www.organojudicial.gob.pa/uploads/wp_repo/blogs.dir/cendoj/ley-1-de-2014.pdf, accessed 2026-10-27
- Decreto Ejecutivo 170 de 27 de octubre de 1993 (income-tax regulations), Gaceta Oficial 22412, Asamblea Nacional de Panamá (Legispan), https://s3-legispan.asamblea.gob.pa/legispan/NORMAS/1990/1993/DECRETO%20EJECUTIVO/Administrador%20Legispan_22412_1993_11_12_MINISTERIO%20DE%20HACIENDA%20Y%20TESORO_170.pdf, accessed 2026-10-27
- Tarifa del Impuesto sobre la Renta, Dirección General de Ingresos (DGI), Ministerio de Economía y Finanzas, https://dgi.mef.gob.pa/DInforme/Tarifa.php, accessed 2026-10-27
- National Internal Revenue Code of 1997, as amended (consolidated), Bureau of Internal Revenue (bir.gov.ph), https://www.bir.gov.ph/tax-code, accessed 2026-10-27
- Ley N° 6380/2019 de Modernización y Simplificación del Sistema Tributario Nacional, Biblioteca y Archivo del Congreso Nacional (bacn.gov.py), https://www.bacn.gov.py/leyes-paraguayas/9332/ley-n-6380-de-modernizacion-y-simplificacion-del-sistema-tributario-nacional, accessed 2026-10-27
- Decreto N° 3184/2019, reglamenta el Impuesto a la Renta Personal (IRP), Dirección Nacional de Ingresos Tributarios (DNIT), https://www.dnit.gov.py/documents/47797/47809/Decreto+N%C2%B0+3184-19.pdf/6eaa47e9-504b-fc0b-6a03-4dc2b267e2a8?t=1681424323603, accessed 2026-10-27
- Seychelles Tax System, Seychelles Revenue Commission (src.gov.sc), https://src.gov.sc/seychelles-tax-system/, accessed 2026-10-28
- Business Tax Act, 2009 (Cap 20), SeyLII, Seychelles Legal Information Institute (seylii.org), https://seylii.org/akn/sc/act/2009/28, accessed 2026-10-28
- Income received from overseas, Inland Revenue Authority of Singapore (IRAS), https://www.iras.gov.sg/taxes/individual-income-tax/basics-of-individual-income-tax/what-is-taxable-what-is-not/income-received-from-overseas, accessed 2026-10-28
- Scenario-based FAQs: I am working for a foreign employer, Inland Revenue Authority of Singapore (IRAS), https://www.iras.gov.sg/taxes/individual-income-tax/employees/scenario-based-faqs-for-working-in-singapore-and-abroad/i-am-working-for-a-foreign-employer, accessed 2026-10-28
- Individual Income Tax rates, Inland Revenue Authority of Singapore (IRAS), https://www.iras.gov.sg/taxes/individual-income-tax/basics-of-individual-income-tax/tax-residency-and-tax-rates/individual-income-tax-rates, accessed 2026-10-28
- Decreto Legislativo 969 of 12 March 2024, Reformas a la Ley del Impuesto sobre la Renta (Diario Oficial 52, Tomo 442, 14 March 2024), Asamblea Legislativa de El Salvador, https://www.asamblea.gob.sv/sites/default/files/documents/decretos/86A64E36-EB7C-4F57-82BC-A289A5D94C33.pdf, accessed 2026-10-28
- Ley de Impuesto sobre la Renta, Decreto Legislativo 134 of 1991 (consolidated text including Decretos 969/2024, 293/2025 and 568/2026), Asamblea Legislativa de El Salvador, https://www.asamblea.gob.sv/sites/default/files/documents/decretos/F7E4B567-1749-45F4-96BB-748A01BF4D14.pdf, accessed 2026-10-28
- Law No 24 of 2003 on Income Tax, People's Assembly of the Syrian Arab Republic (Law No 24 of 2003), https://www.wipo.int/wipolex/en/legislation/details/20751, accessed 2026-10-27
- How do foreigners living in Thailand pay tax? (2024), The Revenue Department of Thailand (rd.go.th), https://www.rd.go.th/fileadmin/user_upload/lorkhor/newspr/2024/FOREIGNERS_PAY_TAX2024.pdf, accessed 2026-10-27
- Revenue Department Order Paw. 161/2566 on income tax under section 41 paragraph 2 (consolidated, Thai), The Revenue Department of Thailand (rd.go.th), https://www.rd.go.th/fileadmin/user_upload/kormor/newlaw/dn161A.pdf, accessed 2026-10-27
- Income Tax Act, Chapter 75:01 (unofficial consolidation updated to 31 December 2014), Ministry of Legal Affairs, Laws of Trinidad and Tobago (laws.gov.tt), https://laws.gov.tt/ttdll-web2/revision/download/79416?type=act, accessed 2026-10-28
- International Tax, Inland Revenue Division, Ministry of Finance, https://www.ird.gov.tt/international-tax, accessed 2026-10-28
- Income Tax Act (所得稅法), amended 11 September 2026, Laws & Regulations Database of the Republic of China (Taiwan), Ministry of Justice, https://law.moj.gov.tw/LawClass/LawAll.aspx?pcode=G0340003, accessed 2026-10-27
- Income Basic Tax Act (所得基本稅額條例), Laws & Regulations Database of the Republic of China (Taiwan), Ministry of Justice, https://law.moj.gov.tw/LawClass/LawAll.aspx?pcode=G0340115, accessed 2026-10-27
- Texto Ordenado 2023 de la DGI, Título 7 (IRPF), consolidated, IMPO, Centro de Información Oficial, https://www.impo.com.uy/bases/todgi2023/101-2024, accessed 2026-10-27
- Texto Ordenado 2023, Título 7, Artículo 24-BIS (Régimen de impatriados. Rentas de capital), IMPO, Centro de Información Oficial, https://www.impo.com.uy/bases/todgi2023/101-2024/24_BIST7, accessed 2026-10-27
- Income Tax Act, Chapter 323 (consolidated as at 31 December 1996), Government of the Republic of Zambia (Laws of Zambia, Chapter 323, revised edition as at 31 December 1996), https://media.zambialii.org/media/legislation/21052/source_file/e7169ecce80aa937/1967-32.pdf, accessed 2026-10-27
- Tax Information (Turnover Tax, PAYE, Withholding Tax, Property Transfer Tax), Zambia Revenue Authority, https://www.zra.org.zm/tax-information/, accessed 2026-10-27
- Income Tax Act [Chapter 23:06], consolidated to 1 December 2024, Zimbabwe Revenue Authority (ZIMRA), https://www.zimra.co.zw/legislation/17-acts?download=4233:income-tax-act-updated-to-1st-dec-2024, accessed 2026-10-27
- Personal Income Tax, The Revenue Department of Thailand (rd.go.th), https://www.rd.go.th/english/6045.html, accessed 2026-10-27
- Revenue Code, Chapter 3 Income Tax (sections 39 to 64, English translation), The Revenue Department of Thailand (rd.go.th), https://www.rd.go.th/english/37749.html, accessed 2026-10-27
- Revenue Department Order Paw. 162/2566 (Thai), The Revenue Department of Thailand (rd.go.th), https://www.rd.go.th/fileadmin/user_upload/kormor/newlaw/dn162A.pdf, accessed 2026-10-27
- Law No 13/2025, 2026 Budget of the Macao SAR, Official Gazette of the Macao SAR (Boletim Oficial, bo.dsaj.gov.mo), https://bo.dsaj.gov.mo/bo/i/2025/52/lei13.asp, accessed 2026-10-28
- Income Tax: who are required to file income tax returns, and income tax rates, Bureau of Internal Revenue (bir.gov.ph), https://www.bir.gov.ph/income-tax, accessed 2026-10-27
- Income and Non-Monetary Benefits Tax, Seychelles Revenue Commission (src.gov.sc), https://src.gov.sc/income-and-non-monetary-benefits-tax/, accessed 2026-10-28
- Finance Act [Chapter 23:04], consolidated to 1 December 2024, Zimbabwe Revenue Authority (ZIMRA), https://www.zimra.co.zw/legislation/17-acts?download=4235:finance-act-updated-to-1st-dec-2024, accessed 2026-10-27
- Inheritance (transfer) tax: laws and decisions, Ministry of Finance, Lebanon (finance.gov.lb), https://www.finance.gov.lb/en-us/Taxation/LRT/Inherit/Pages/default.aspx, accessed 2026-10-27
- Decreto N° 3181/2019, reglamenta el Impuesto a la Renta de No Residentes (INR), Dirección Nacional de Ingresos Tributarios (DNIT), https://www.dnit.gov.py/documents/47797/47809/Decreto+N%C2%B0+3181-19.pdf/1382f732-af6b-de2a-0fe3-8ce02a0eb2ff?t=1681424114127, accessed 2026-10-27
- Reglamento de la Ley del Impuesto sobre la Renta, Acuerdo 799 of 19 November 1969, Secretaría de Estado en los Despachos de Economía y Hacienda, Honduras (Acuerdo 799), https://honduras.eregulations.org/media/HondurasRreglamentoLISR.pdf, accessed 2026-10-27
- Decreto 6-2026, Derogatoria de la Ley sobre el Impuesto de Herencias, Legados y Donaciones (Diario de Centro América, 2 March 2026), Congreso de la República de Guatemala, https://www.congreso.gob.gt/assets/uploads/info_legislativo/decretos/62c33-6-2026.pdf, accessed 2026-10-27
- Ley 171-07 sobre Incentivos Especiales a los Pensionados y Rentistas de Fuente Extranjera, Dirección General de Impuestos Internos (DGII), https://dgii.gov.do/legislacion/leyesTributarias/Documents/Leyes%20de%20Incentivos%20y%20Fomentos/171-07.pdf, accessed 2026-10-27
- Retired Persons (Incentives) Act, Chapter 62, Revised Edition 2020, Attorney General's Ministry, Government of Belize, https://agm.gov.bz/uploads/laws/63976e60333b3_Cap_62_Retired_Persons__Incentives__Act.pdf, accessed 2026-10-27
- Government of Georgia Ordinance No 415 of 29 December 2010 on Special Taxation Regimes, Legislative Herald of Georgia (matsne.gov.ge), https://matsne.gov.ge/ka/document/view/1164635, accessed 2026-10-27
- Nostos tax profiles (152 countries), Navoy, https://nostos.navoy.io/data, accessed 2026-10-28
About the Author
Haroun Moula
Haroun Moula is the founder and CEO of Navoy. Before Navoy, he worked in luxury travel with VVIPs and high-profile travelers. He built Navoy to bring curated, adaptive trip planning to more travelers through an AI travel agent that plans and books core trip parts in one place.