Key Takeaways
- 86 of 152 countries have no inheritance tax as such. They include Sweden, Norway, Austria, Estonia, Czechia, Cyprus, the UAE, Singapore, Australia, Canada and Mexico, but in 20 of them heirs can still owe transfer duty, income tax or tax on gains at death.
- Only 11 countries levy an annual net wealth tax in 2026. They are Algeria, Argentina, Bolivia, Colombia, Norway, Spain, Suriname, Switzerland, Tunisia, Uruguay and Venezuela.
- In Europe, only Norway, Spain and Switzerland have a net wealth tax. Belgium, Italy, the Netherlands, Romania and Türkiye tax some wealth through narrower annual levies instead.
- Most European countries with an inheritance tax exempt the spouse and children. Belgium, Finland, Germany, Italy, the Netherlands, Türkiye and the UK are among those that still tax what children inherit.
- Moving abroad does not end your home country's claim at once. The UK keeps a long-term resident's worldwide assets in scope for 3 to 10 tax years after they leave, Germany for 5 years for its citizens, and the Netherlands for 10 years for Dutch nationals.
Of the 152 countries in our tax data, 86 have no inheritance tax as such, including Sweden, Norway, Austria, Estonia, Czechia, Cyprus, the UAE, Singapore, Australia, Canada and Mexico. Only 11 still charge an annual net wealth tax: Algeria, Argentina, Bolivia, Colombia, Norway, Spain, Suriname, Switzerland, Tunisia, Uruguay and Venezuela. But "no inheritance tax" does not always mean heirs pay nothing: in 20 of those 86 countries an inheritance can still trigger transfer duty, income tax, tax on gains at death or a regional tax.
We built these lists from the wealth section of the 152 country tax profiles behind Nostos, Navoy's free city chooser, each checked against the tax authority or the law. Rules verified against official sources on 27 and 28 October 2026. This is general information, not tax advice; US citizens are taxed by citizenship, and home-country exit and residence rules can change the answer, so confirm your case with a qualified adviser.
Which countries have a wealth tax in 2026?
A net wealth tax is an annual tax on everything you own minus your debts. Eleven countries still levy one on individuals. Residents usually pay on worldwide assets; Uruguay is the exception and taxes only assets in Uruguay.
| Country | Starts above | 2026 rate | Notes |
|---|---|---|---|
| Algeria | $739,400 (DZD 100 million) | 0.15% to 1% by slice | Mainly real estate and luxury items; most shares left out |
| Argentina | $65,000 (ARS 100 million) at 2023 values, indexed (ARS 293 million for 2024) | 0.5% to 0.75% | Flat 0.25% for 2027 |
| Bolivia | $2.5 million (Bs30 million) | 1.4% to 2.4% of the whole amount, less a fixed sum | Residents worldwide, others on Bolivian assets |
| Colombia | About $1.19 million (72,000 UVT, COP 3.77 billion) | 0.5% to 1.5% | Top rate falls to 1% from 2027 |
| Norway | $204,700 (NOK 1.9 million); $409,400 (NOK 3.8 million) for couples | 1.0%, then 1.1% above $2.3 million (NOK 21.5 million) | Main home valued at 25% |
| Spain | $779,100 (€700,000) plus $333,900 (€300,000) for the main home | 0.2% to 3.5%, plus 1.7% to 3.5% solidarity tax on taxable wealth above $3.3 million (€3 million), after the allowance | Regional rebates, e.g. Madrid and Andalucía |
| Suriname | Not confirmed | Not confirmed | Still collected on a small scale |
| Switzerland | Set by each canton; $97,760 (CHF 81,000) in Zurich | Top rates about 0.12% (Nidwalden) to 0.86% (Geneva city) | Zurich city top rate 0.642% |
| Tunisia | $995,600 (TND 3 million) | 0.5%, 1% above $1.7 million (TND 5 million) | Replaced a narrower 2023 tax on 1 January 2026; main home and bank deposits exempt |
| Uruguay | About $165,000 (UYU 6,653,000, 2025) | 0.1% | Uruguayan assets only |
| Venezuela | About $1.74 million (36 million UT) | 0.25% | Only for designated "special taxpayers" |
Two figures are uncertain. Suriname's consolidated law still states 8 per 1,000 above allowances in old guilders, and we could not confirm the current rate. Venezuela's threshold may have been raised to 150 million UT by a 2019 reprint that the official gazette portal would not open. Tunisia's law also leaves unclear whether 1% applies to the whole value above $1.7 million (TND 5 million) or only to the slice above it.
If you are weighing these, the tax section on the Oslo, Zurich and Madrid city pages shows how each country treats a newcomer.
Scouting a base first? Plan the trip free with Navoy and compare hotels in Dubai.
Which countries tax wealth without calling it a wealth tax?
Six more countries in our data have no general wealth tax but charge a yearly levy on certain assets:
- Belgium: 0.30% a year (0.15% for periods ending before 1 June 2026) on securities accounts averaging more than $1.1 million (€1 million), on accounts held anywhere in the world.
- Italy: IVAFE of 0.2% a year on foreign financial products and IVIE of 1.06% on foreign property, paid by residents. See the Milan page.
- Netherlands: box 3 income tax of 36% on a deemed return, about 0.46% to 2.16% of net assets above $66,060 (€59,357) a year in 2026.
- Romania: 0.9% a year on the part of a home's taxable value above $520,700 (RON 2,500,000), and on the part of a car's price above $78,100 (RON 375,000) for its first five years.
- Seychelles: 0.5% a year of market value on homes owned by non-Seychellois.
- Türkiye: a valuable housing tax of 0.3% to 1% on homes with a tax value above $355,400 (TL 17,711,000), unless it is your only home in Türkiye.
France and Portugal come close: France's IFI taxes net real estate only, once it exceeds $1.4 million (€1.3 million), at 0.5% to 1.5%, and Portugal's AIMI charges 0.7% to 1.5% a year on Portuguese property above $667,800 (€600,000) per person.
Which European countries have no inheritance tax?
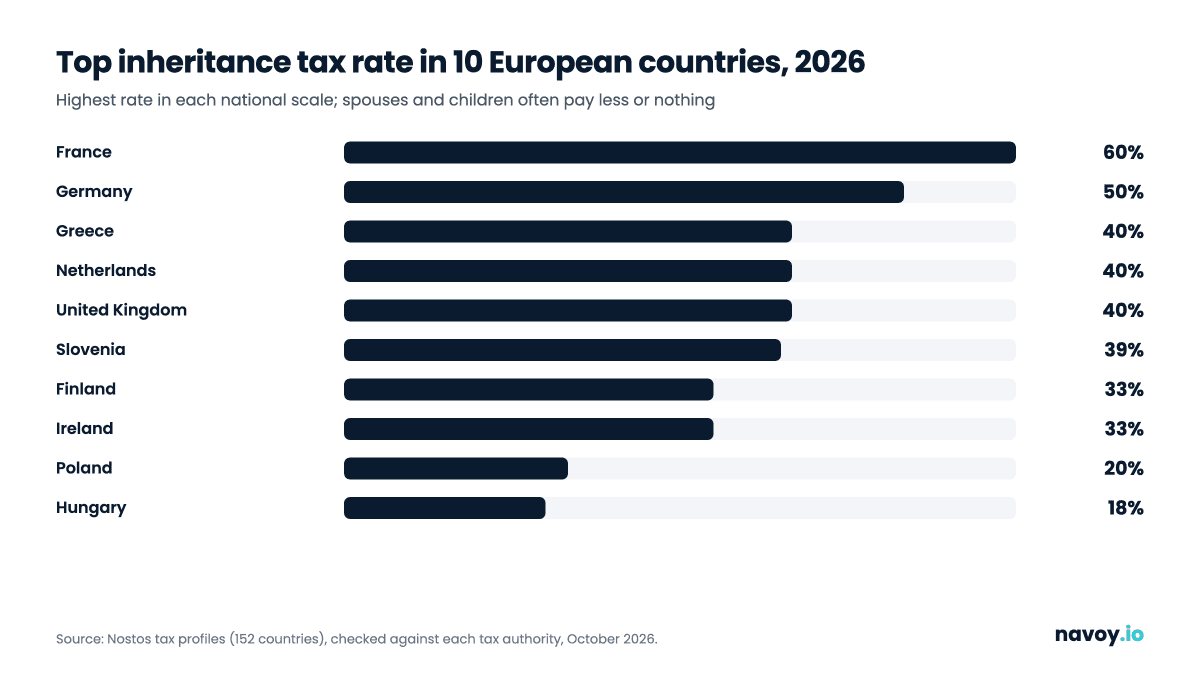
Sixteen of the 43 European countries in Nostos (including Türkiye, Georgia and Russia) have no inheritance tax as such. Most of the rest exempt the spouse and children, so the column that matters for most families is the third one.
| Country | Inheritance tax | Spouse and children | Wealth tax or levy |
|---|---|---|---|
| Andorra | No | Not taxed | None |
| Austria | No (since 2008) | Inherited property pays 0.5% to 3.5% transfer tax | None |
| Belarus | No | Not taxed (notary fee) | None |
| Cyprus | No (since 2000) | Not taxed | None |
| Czechia | No | Not taxed | None |
| Estonia | No | Not taxed | None |
| Georgia | No separate tax | Exempt from income tax | None |
| Latvia | No | Not taxed | None |
| Malta | No | 5% duty on inherited Maltese property | None |
| Moldova | No separate tax | Income tax rules not confirmed | None |
| Montenegro | No | Exempt from property transfer tax | None |
| Norway | No (since 2014) | Not taxed | Net wealth tax |
| Romania | No | 1% on Romanian property if the succession takes over 2 years | 0.9% on high-value homes and cars |
| Russia | No | Not taxed | None |
| Slovakia | No | Not taxed | None |
| Sweden | No (since 2005) | Not taxed | None |
| Albania | 15% | Exempt | None |
| Belgium | Regional | 3% to 30% (3% to 27% in Flanders) | Securities accounts tax |
| Bosnia and Herzegovina | Cantonal (8% in Sarajevo) | Exempt | None |
| Bulgaria | Municipal | Exempt | None |
| Croatia | 4% | Exempt | None |
| Denmark | 15% and up | Spouse exempt; children 15% above $58,420 (DKK 392,300) | None |
| Finland | 7% to 33% | 7% to 19% on shares of $33,390 (€30,000) or more | None |
| France | 5% to 60% | Spouse exempt; children 5% to 45% above $111,300 (€100,000) each | IFI on real estate |
| Germany | 7% to 50% | 7% to 30% above $556,500 (€500,000) for a spouse or $445,200 (€400,000) for a child | None |
| Greece | 1% to 40% | 0% up to $167,000 (€150,000), then 1% to 10% | None |
| Hungary | 18% (9% on a home) | Exempt | None |
| Iceland | 10% | Spouse exempt; 10% above $55,650 (ISK 6.79 million) per estate | None |
| Ireland | 33% | Spouse exempt; child taxed above $467,500 (€420,000) | None |
| Italy | 4% to 8% | 4% above $1.1 million (€1 million) each | IVAFE and IVIE on foreign assets |
| Kosovo | Through income tax | Exempt | None |
| Lithuania | 5% to 10% | Exempt | None |
| Luxembourg | Yes | Exempt on the legal share | None |
| Netherlands | 10% to 40% | 10% to 20% above $921,600 (€828,035) for a partner or $29,190 (€26,230) for a child | Box 3 deemed return |
| North Macedonia | Municipal | Exempt | None |
| Poland | 3% to 20% | Exempt if reported within 6 months | None |
| Portugal | 10% stamp duty on Portuguese assets | Exempt | AIMI on property above $667,800 (€600,000) |
| Serbia | 1.5% to 2.5% | Exempt | None |
| Slovenia | 5% to 39% | Exempt | None |
| Spain | Regional | 99% to 100% relief in most regions | Net wealth tax |
| Switzerland | Cantonal | Spouse exempt; children in most cantons | Cantonal wealth tax |
| Türkiye | 1% to 10% | Taxed above $58,330 (TL 2,907,136) each | Valuable housing tax |
| United Kingdom | 40% | Spouse exempt; 40% above $432,800 (£325,000), up to $665,800 (£500,000) with a home | None |
The Stockholm, Tallinn, Prague and Valletta pages show the full picture for four of the no-inheritance-tax countries.
Which countries have no inheritance or estate tax outside Europe?
| Region | No tax on inheritances | No inheritance tax, but heirs can still pay |
|---|---|---|
| Middle East | Bahrain, Jordan, Kuwait, Oman, Qatar, Saudi Arabia, UAE | None |
| Asia | Armenia, Bangladesh, Bhutan, Brunei, China, Hong Kong, India, Kazakhstan, Kyrgyzstan, Macau, Malaysia, Maldives, Mongolia, Myanmar, Nepal, Pakistan, Singapore, Sri Lanka, Tajikistan | Azerbaijan, Cambodia, Indonesia, Laos, Uzbekistan |
| Africa | Benin, Gambia, Kenya, Madagascar, Mauritius, Namibia, Nigeria, Rwanda, Tanzania, Uganda, Zambia | DR Congo, Egypt, Ethiopia, Ghana, Morocco, Seychelles |
| Americas | Aruba, Bahamas, Barbados, Belize, Costa Rica, El Salvador, Guatemala, Honduras, Mexico, Panama, Paraguay, Peru, Trinidad and Tobago | Argentina, Canada, Puerto Rico |
| Oceania | Australia, Fiji, New Zealand, Samoa, Vanuatu | French Polynesia |
Guatemala is the newest entry: it repealed its inheritance, legacy and gift tax in 2026. The US is not on the list: its federal estate tax charges up to 40% after a $15,000,000 exemption per person for 2026. In Iraq (federal), Suriname and Syria we could not confirm whether an inheritance tax is applied. Mongolia's tax code still names one, but no law in force sets it.
When does "no inheritance tax" still cost heirs money?
In 20 countries in our data with no inheritance tax, an inheritance can still be taxed:
- Transfer duty on inherited property: Malta (5%), Austria (0.5% to 3.5%), Montenegro (3% to 6%, close family exempt), Indonesia (up to 5%), Cambodia (4%, close family exempt), Egypt (2.5% on bequests of property except to parents, spouse or children), Romania (1% if the succession is not completed within 2 years), French Polynesia (2% on bequests under a will), and registration or stamp duties in DR Congo, Morocco and, for non-citizens, the Seychelles.
- Income tax on the inheritance: Georgia, Azerbaijan (14% above $11,770 (AZN 20,000) from non-family), Laos (2% outside close relatives) and Uzbekistan (12% on property passed between people who are not close relatives).
- Tax on gains at death: Canada treats the deceased as having sold everything at market value, unless it goes to a spouse, and Ontario adds probate fees; Ghana also treats a death as a sale at market value, except for assets passing to a spouse; Ethiopia can charge 15% capital gains tax on buildings and shares in the estate.
- Another government's tax: Argentina's Province of Buenos Aires charges 1.603% to 9.513% on inheritances, and US citizens who move to Puerto Rico from the mainland stay inside the US federal estate tax.
The UAE charges only a flat $272 (AED 1,000) per property to transfer it to heirs in Dubai, which is a fee, not a tax. See the Dubai page.
Whose inheritance tax applies: where the deceased lived, the heir lives or the assets are?
Often all three. Moving to a no-tax country protects you less than it seems:
- United Kingdom: since 6 April 2025 the test is residence, not domicile. Worldwide assets are in scope once you have been UK resident for 10 of the previous 20 tax years, and that status lasts 3 to 10 tax years after you leave. UK assets are always in scope. See London.
- Germany: the whole transfer is taxed if either the deceased or the heir lives in Germany, and German citizens stay fully liable for 5 years after moving abroad.
- Netherlands: Dutch nationals are treated as resident for 10 years after emigrating.
- France: an heir domiciled in France for 6 of the last 10 years is taxed on gifts and inheritances from abroad.
- Belgium: the rates follow the region where the deceased lived longest in the last 5 years.
- United States: citizens and US-domiciled people are taxed on worldwide estates; other people only on US assets, with a filing duty once those exceed $60,000.
Real estate is almost always taxed where it sits, so a Spanish flat stays inside Spanish inheritance tax wherever you live.
Which countries do not tax foreigners on inheritances from abroad?
Several taxing countries mostly leave a foreigner's foreign assets alone. Portugal's 10% stamp duty covers only assets located in Portugal, as the Lisbon page explains. Türkiye taxes property in Türkiye and property of Turkish citizens. Thailand taxes foreigners only on Thai assets, unless they have a domicile in Thailand under immigration law. Ireland treats a foreign-domiciled person as resident only after 5 consecutive years. Holders of Italy's flat tax for new residents pay inheritance tax only on Italian assets.
If you are using these rules to pick a base for the next few years, compare cities on Nostos, then plan the trip free with Navoy, check hotels in Dubai and look up flights to Dubai. Our guide to digital nomad taxes covers the income tax side.
Frequently asked questions
Which countries have no inheritance tax?
In the Nostos data, 86 of 152 countries have no inheritance tax as such. In Europe they are Andorra, Austria, Belarus, Cyprus, Czechia, Estonia, Georgia, Latvia, Malta, Moldova, Montenegro, Norway, Romania, Russia, Slovakia and Sweden. Elsewhere they include the UAE and the other Gulf states, Singapore, Hong Kong, Malaysia, India, China, Australia, New Zealand, Canada, Mexico, Costa Rica and Panama. In some of them, such as Malta, Austria and Canada, heirs can still pay transfer duty or tax on gains.
Which European countries have a wealth tax in 2026?
Three: Norway, at 1.0% above $204,700 (NOK 1.9 million) of net wealth and 1.1% above $2.3 million (NOK 21.5 million); Spain, at 0.2% to 3.5% after a $779,100 (€700,000) allowance, plus a solidarity tax on taxable wealth above $3.3 million (€3 million); and Switzerland, where every canton levies one. France taxes only net real estate above $1.4 million (€1.3 million), and Belgium, Italy and the Netherlands tax securities accounts, foreign assets or deemed returns instead.
Does the US have an estate tax?
Yes. The federal estate and gift tax charges up to 40% for people domiciled in the US and for US citizens wherever they live, after a combined exemption of $15,000,000 per person for 2026. Non-residents who are not citizens are taxed only on US-situs assets, and their estates must file once those exceed $60,000. Some states, such as New York, add their own estate tax.
Do I escape inheritance tax by moving to a country without one?
Not always. Inheritance tax often follows where the deceased lived, where the heir lives and where the assets are. Your home country may keep taxing you after you leave, as the UK does for 3 to 10 years and Germany for 5 years for citizens, and property in a taxing country stays taxable there. Check both countries' rules with a qualified adviser.
Sources
- Inheritance Tax if you're a long-term UK resident, HM Revenue & Customs, GOV.UK, https://www.gov.uk/guidance/inheritance-tax-if-youre-a-long-term-uk-resident, accessed 2026-10-28
- Inheritance Tax, GOV.UK, https://www.gov.uk/inheritance-tax, accessed 2026-10-27
- Formuesskatt og verdsettingsrabatter (satser 2026), Skatteetaten (Norwegian Tax Administration), https://www.skatteetaten.no/satser/formuesskatt/?year=2026, accessed 2026-10-28
- Inheritance tax is abolished, Skatteetaten (Norwegian Tax Administration), https://www.skatteetaten.no/en/person/taxes/get-the-taxes-right/gift-and-inheritance/inheritance-tax-is-abolished/, accessed 2026-10-27
- Ley 19/1991, del Impuesto sobre el Patrimonio (texto consolidado), Agencia Estatal Boletín Oficial del Estado (BOE), https://www.boe.es/buscar/act.php?id=BOE-A-1991-14392, accessed 2026-10-27
- Ley 38/2022, art. 3 (Impuesto Temporal de Solidaridad de las Grandes Fortunas), texto consolidado, Agencia Estatal Boletín Oficial del Estado (BOE), https://www.boe.es/buscar/act.php?id=BOE-A-2022-22684, accessed 2026-10-28
- Bundesgesetz über die Harmonisierung der direkten Steuern der Kantone und Gemeinden (StHG), SR 642.14, Swiss Federal Chancellery, Fedlex, https://www.fedlex.admin.ch/eli/cc/1991/1256_1256_1256/de, accessed 2026-10-27
- Dossier Steuerinformationen: Erbschafts- und Schenkungssteuern (Stand 1. Januar 2025), Federal Tax Administration (ESTV), https://www.estv2.admin.ch/stp/ds/d-erbschaft-schenkung-de.pdf, accessed 2026-10-27
- Ley 23.966, Título VI: Impuesto sobre los Bienes Personales (texto actualizado), ARCA, Biblioteca Electrónica, https://biblioteca.afip.gob.ar/dcp/TOR_C_023966_1997_03_26, accessed 2026-10-27
- Ley 27.743, Medidas fiscales paliativas y relevantes, ARCA, Biblioteca Electrónica, https://biblioteca.afip.gob.ar/dcp/LEY_C_027743_2024_06_27, accessed 2026-10-27
- ¿Qué grava el Impuesto a la Transmisión Gratuita de Bienes (TGB)?, ARBA, Agencia de Recaudación de la Provincia de Buenos Aires, https://web.arba.gov.ar/preguntas-frecuentes/que-grava-el-impuesto-la-transmision-gratuita-de-bienes-tgb, accessed 2026-10-27
- Ley N° 1357 de 28 de diciembre de 2020, Impuesto a las Grandes Fortunas (IGF), Servicio de Impuestos Nacionales (Bolivia), https://www.impuestos.gob.bo/wp-content/uploads/2025/11/LEY1357.pdf, accessed 2026-10-27
- Estatuto Tributario, artículos 292-3 a 297-3 (impuesto al patrimonio), DIAN (Colombia), https://normograma.dian.gov.co/dian/compilacion/docs/estatuto_tributario.htm#292-3, accessed 2026-10-27
- Law No 20-07 of 4 June 2020, Supplementary Finance Law for 2020, Journal officiel de la République algérienne, https://www.joradp.dz/FTP/jo-francais/2020/F2020033.pdf, accessed 2026-10-27
- Vermogensbelasting 1944 (consolidated text), De Nationale Assemblée (Suriname), https://www.dna.sr/media/dqqltkkx/vermogensbelasting_1944.pdf, accessed 2026-10-28
- Law No 2025-17 of 12 December 2025, Finance Law for 2026, Ministry of Finance of Tunisia, https://www.finances.gov.tn/sites/default/files/2026-01/115725.pdf, accessed 2026-10-27
- Texto Ordenado 2023, Título 14 (Impuesto al Patrimonio), Artículo 53, IMPO (Uruguay), https://www.impo.com.uy/bases/todgi2023/101-2024/53_T14, accessed 2026-10-27
- Decreto N° 334/025 (mínimo no imponible del Impuesto al Patrimonio, año 2025), IMPO (Uruguay), https://www.impo.com.uy/bases/decretos/334-2025, accessed 2026-10-27
- Ley Constitucional que crea el Impuesto a los Grandes Patrimonios, Gaceta Oficial N° 41.667, Gaceta Oficial de la República Bolivariana de Venezuela, https://www.gacetaoficial.gob.ve/gacetas/41667, accessed 2026-10-28
- Wet van 17 februari 2021 houdende de invoering van een jaarlijkse taks op de effectenrekeningen, Belgisch Staatsblad, https://www.ejustice.just.fgov.be/eli/wet/2021/02/17/2021040569/staatsblad, accessed 2026-10-27
- Programmawet van 30 mei 2026, artikel 6, Belgisch Staatsblad, https://www.ejustice.just.fgov.be/eli/wet/2026/05/30/2026003986/staatsblad, accessed 2026-10-27
- Payment of inheritance tax and estate duties, FPS Finance (Belgium), https://fin.belgium.be/en/private-individuals/death/inheritance-tax, accessed 2026-10-27
- Ivafe: Base imponibile e aliquote, Agenzia delle Entrate (Italy), https://www.agenziaentrate.gov.it/portale/schede/pagamenti/imposta-valore-att-estero-ivafe/base-imponibile-e-aliquote-scheda-ivafe, accessed 2026-10-28
- Ivie: Base imponibile e aliquota, Agenzia delle Entrate (Italy), https://www.agenziaentrate.gov.it/portale/schede/pagamenti/imposta-sul-valore-degli-immobili-estero-ivie/base-imponibile-e-aliquota-scheda-ivie, accessed 2026-10-27
- Imposta di successione: Aliquote e franchigie, Agenzia delle Entrate (Italy), https://www.agenziaentrate.gov.it/portale/schede/pagamenti/imposta-di-successione/aliquote-e-franchigie, accessed 2026-10-27
- Voorlopige aanslag 2026: gebruikte tarieven en heffingskortingen, Belastingdienst (Netherlands), https://www.belastingdienst.nl/wps/wcm/connect/nl/voorlopige-aanslag/content/voorlopige-aanslag-tarieven-en-heffingskortingen, accessed 2026-10-27
- Successiewet 1956, artikelen 1 en 3, Overheid.nl, https://wetten.overheid.nl/BWBR0002226/2026-01-01, accessed 2026-10-27
- Legea nr. 227/2015 privind Codul fiscal, ANAF (Romania), https://static.anaf.ro/static/10/Anaf/legislatie/Cod_fiscal_norme_2023.htm, accessed 2026-10-27
- Immovable Property Tax (Increase in Tax Rate) Order, 2023 (S.I. 39 of 2023), Official Gazette of Seychelles, https://www.gazette.sc/sites/default/files/2023-05/SI%2039%202023%20-%20Immovable%20Property%20Tax%20%28Increase%20in%20Tax%20Rate%29%20Order%202023.pdf, accessed 2026-10-28
- Stamp Duty (Exemption) Order, 2019, Ministry of Finance, Government of Seychelles, https://www.finance.gov.sc/stamp-duty-exemption/, accessed 2026-10-28
- Property Tax Law No 1319 (Emlak Vergisi Kanunu), Mevzuat Bilgi Sistemi (Türkiye), https://www.mevzuat.gov.tr/mevzuatmetin/1.5.1319.pdf, accessed 2026-10-27
- Inheritance and Transfer Tax Law No 7338, Mevzuat Bilgi Sistemi (Türkiye), https://www.mevzuat.gov.tr/mevzuatmetin/1.3.7338.pdf, accessed 2026-10-27
- Impôt sur la fortune immobilière (IFI), Service-Public.fr, https://www.service-public.gouv.fr/particuliers/vosdroits/F138, accessed 2026-10-27
- Droits de succession (barème et abattements), Service-Public.fr, https://www.service-public.gouv.fr/particuliers/vosdroits/F14198, accessed 2026-10-27
- BOI-ENR-DMTG-10-10-30: Champ d'application territorial (article 750 ter CGI), BOFiP-Impôts (France), https://bofip.impots.gouv.fr/bofip/3543-PGP.html/identifiant=BOI-ENR-DMTG-10-10-30-20120912, accessed 2026-10-27
- Erbschaftsteuer- und Schenkungsteuergesetz (ErbStG) § 2, gesetze-im-internet.de (Germany), https://www.gesetze-im-internet.de/erbstg_1974/__2.html, accessed 2026-10-27
- Boafgiftsloven §§ 1, 3, 22, 23 and 25, Retsinformation (Denmark), https://www.retsinformation.dk/eli/lta/2023/11, accessed 2026-10-27
- Inheritance tax calculator, Verohallinto (Finnish Tax Administration), https://www.vero.fi/en/individuals/property/inheritance/inheritance-tax-calculator/, accessed 2026-10-27
- Φορολογία Κεφαλαίου (capital taxation guide), Ministry of National Economy and Finance (Greece), https://minfin.gov.gr/forologiki-politiki/forologikos-odigos/forologia-kefalaiou/, accessed 2026-10-27
- Capital Acquisitions Tax Notes for Guidance, Part 3: Inheritance Tax, Revenue (Ireland), https://www.revenue.ie/en/tax-professionals/documents/notes-for-guidance/cat/2024/part03.pdf, accessed 2026-10-27
- CAT thresholds, Revenue (Ireland), https://www.revenue.ie/en/gains-gifts-and-inheritance/cat-thresholds-rates-and-aggregation-rules/cat-thresholds.aspx, accessed 2026-10-28
- Código do IMI, artigo 135.º-F (AIMI: taxa), Portal das Finanças (Portugal), https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/cimi/Pages/cimi135f.aspx, accessed 2026-10-28
- Código do IMI, artigo 135.º-C (AIMI: valor tributável), Portal das Finanças (Portugal), https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/cimi/Pages/cimi135c.aspx, accessed 2026-10-27
- Erfðafjárskattur, Ísland.is (Iceland), https://island.is/erfdafjarskattur, accessed 2026-10-27
- Paveldimo turto mokestis, Valstybinė mokesčių inspekcija (Lithuania), https://www.vmi.lt/evmi/paveldimo-turto-mokestis, accessed 2026-10-27
- Identifier les impôts dus en matière de droit de succession, Guichet.lu (Luxembourg), https://guichet.public.lu/fr/citoyens/sante/fin-vie/deces/droits-succession-heritage.html, accessed 2026-10-28
- Inheritance and Gifts Tax, Porezna uprava (Croatia), https://porezna-uprava.gov.hr/en/inheritance-and-gifts-tax-7367/7367, accessed 2026-10-27
- Local Taxes and Fees Act (English translation), Ministry of Finance of Bulgaria, https://minfin.bg/upload/60568/Local_Taxes_and_Fees_Act.pdf, accessed 2026-10-27
- Property tax (guide), Public Revenue Office (North Macedonia), https://www.ujp.gov.mk/en/vodic/category/415, accessed 2026-10-27
- Zakon o porezima na imovinu, Pravno-informacioni sistem Republike Srbije, https://www.pravno-informacioni-sistem.rs/SlGlasnikPortal/eli/rep/sgrs/skupstina/zakon/2001/26/1/reg, accessed 2026-10-27
- Davek od premoženja, Financial Administration of the Republic of Slovenia (FURS), https://www.fu.gov.si/davki_in_druge_dajatve/podrocja/davek_od_premozenja/, accessed 2026-10-27
- Código do Imposto do Selo, artigo 4.º (Territorialidade), Portal das Finanças (Portugal), https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/selo/Pages/selo4.aspx, accessed 2026-10-27
- Código do Imposto do Selo, artigo 6.º (Isenções), Portal das Finanças (Portugal), https://info.portaldasfinancas.gov.pt/pt/informacao_fiscal/codigos_tributarios/selo/Pages/selo6.aspx, accessed 2026-10-27
- Ligj nr. 29/2023 Për tatimin mbi të ardhurat, Qendra e Botimeve Zyrtare (Albania), https://qbz.gov.al/eli/ligj/2023/03/30/29, accessed 2026-10-27
- Zakon o porezu na promet nekretnina i porezu na naslijeđe i poklone (Kanton Sarajevo), Skupština Kantona Sarajevo, https://skupstina.ks.gov.ba/sites/default/files/2024-08/zakon_o_porezu_nekretnine.pdf, accessed 2026-10-27
- Ligji Nr. 05/L-028 për Tatimin në të Ardhurat Personale, Gazeta Zyrtare e Republikës së Kosovës, https://gzk.rks-gov.net/ActDocumentDetail.aspx?ActID=11014, accessed 2026-10-28
- Erbschaftssteuer, oesterreich.gv.at (Federal Chancellery of Austria), https://www.oesterreich.gv.at/de/lexicon/E/Seite.991707, accessed 2026-10-27
- Slopad arvsskatt och gåvoskatt (Proposition 2004/05:25), Sveriges riksdag, https://www.riksdagen.se/sv/dokument-och-lagar/dokument/proposition/slopad-arvsskatt-och-gavoskatt_gs0325/html/, accessed 2026-10-27
- Income Tax Act (Tulumaksuseadus), Riigi Teataja (Estonia), https://www.riigiteataja.ee/en/eli/530012014003/consolide/current, accessed 2026-10-27
- Zákon č. 586/1992 Sb., o daních z příjmů, e-Sbírka (Czechia), https://e-sbirka.gov.cz/sb/1992/586, accessed 2026-10-27
- Zákon č. 595/2003 Z. z. o dani z príjmov, Slov-Lex (Slovakia), https://static.slov-lex.sk/static/SK/ZZ/2003/595/20260101.html, accessed 2026-10-27
- Ο Περί Φορολογίας των Κληρονομιών Νόμος του 1962 (67/1962), consolidated, Tax Department (Cyprus), https://www.gov.cy/media/sites/167/2026/07/%CE%9F-%CE%A0%CE%B5%CF%81%CE%AF-%CE%A6%CE%BF%CF%81%CE%BF%CE%BB%CE%BF%CE%B3%CE%AF%CE%B1%CF%82-%CF%84%CF%89%CE%BD-%CE%9A%CE%BB%CE%B7%CF%81%CE%BF%CE%BD%CE%BF%CE%BC%CE%B9%CF%8E%CE%BD-%CE%9D%CF%8C%CE%BC%CE%BF%CF%82-%CF%84%CE%BF%CF%85-1962-67_1962.pdf, accessed 2026-10-27
- Duty on Documents and Transfers Act (Cap. 364), Laws of Malta, https://legislation.mt/eli/cap/364/eng, accessed 2026-10-27
- Zakon o porezu na promet nepokretnosti, Službeni list Crne Gore, https://www.sluzbenilist.me/propisi/335902, accessed 2026-10-27
- Tax Code of Georgia (consolidated version of 15 October 2026), Legislative Herald of Georgia, https://matsne.gov.ge/en/document/view/1043717, accessed 2026-10-27
- Sistema tributari, Govern d'Andorra, https://www.govern.ad/ca/tematiques/impostos-taxes-i-duana/impostos-en-andorra/sistema-tributari, accessed 2026-10-28
- Налог на доходы физических лиц (НДФЛ), Федеральная налоговая служба (Russia), https://www.nalog.gov.ru/rn77/taxation/taxes/ndfl/, accessed 2026-10-27
- Налоговый кодекс Республики Беларусь (Особенная часть), pravo.by, https://pravo.by/document/?guid=3871&p0=hk0900071, accessed 2026-10-28
- Latvijas rezidenti ārvalstīs, Valsts ieņēmumu dienests (Latvia), https://www.vid.gov.lv/lv/latvijas-rezidenti-arvalstis, accessed 2026-10-28
- Tax Code of the Republic of Moldova No 1163/1997, legis.md, https://www.legis.md/cautare/downloadpdf/79283, accessed 2026-10-28
- Inheritance Title Transfer, Dubai Land Department, https://dubailand.gov.ae/en/eservices/inheritance-title-transfer/, accessed 2026-10-27
- Estate Duty FAQs, Inland Revenue Authority of Singapore, https://www.iras.gov.sg/taxes/other-taxes/estate-duty/faqs, accessed 2026-10-28
- If you are a beneficiary of a deceased estate, Australian Taxation Office, https://www.ato.gov.au/individuals-and-families/deceased-estates/if-you-are-a-beneficiary-of-a-deceased-estate, accessed 2026-10-27
- Taxable capital gains on property, investments, and belongings (someone who died), Canada Revenue Agency, https://www.canada.ca/en/revenue-agency/services/tax/individuals/life-events/doing-taxes-someone-died/prepare-returns/report-income/capital-gains.html, accessed 2026-10-27
- Instructions for Form 706 (07/2026), Internal Revenue Service, https://www.irs.gov/instructions/i706, accessed 2026-10-27
- Frequently asked questions on estate taxes for nonresidents not citizens of the United States, Internal Revenue Service, https://www.irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-estate-taxes-for-nonresidents-not-citizens-of-the-united-states, accessed 2026-10-27
- Inheritance Tax Act B.E. 2558 (2015), English translation, The Revenue Department of Thailand, https://www.rd.go.th/fileadmin/user_upload/kormor/eng/ITA_Kung_Proofed.pdf, accessed 2026-10-27
- Decreto 6-2026, Derogatoria de la Ley sobre el Impuesto de Herencias, Legados y Donaciones, Congreso de la República de Guatemala, https://www.congreso.gob.gt/assets/uploads/info_legislativo/decretos/62c33-6-2026.pdf, accessed 2026-10-27
- Estate Administration Tax, Government of Ontario, https://www.ontario.ca/page/estate-administration-tax, accessed 2026-10-27
- Law No 151 of 2026 amending the Income Tax Law, Egyptian Tax Authority, https://eta.gov.eg/sites/default/files/2026-08/law.no_.151.of_.2026.pdf, accessed 2026-10-27
- Undang-Undang Nomor 1 Tahun 2022, JDIH Kementerian Keuangan (Indonesia), https://jdih.kemenkeu.go.id/dok/uu-1-tahun-2022, accessed 2026-10-27
- Stamp Duty (tax types guide), General Department of Taxation (Cambodia), https://www.tax.gov.kh/kh/article?key=w7SPL5W5545044x461, accessed 2026-10-27
- Law on Income Tax (amended) No 88/NA of 25 June 2025, Lao Official Gazette, https://www.laoofficialgazette.gov.la/kcfinder/upload/files/88-25-6-2025_0001.pdf, accessed 2026-10-27
- Tax Code of the Republic of Azerbaijan (consolidated), Ministry of Justice of Azerbaijan, e-qanun.az, https://e-qanun.az/framework/46948, accessed 2026-10-28
- Tax Code of the Republic of Uzbekistan (consolidated to 21 October 2026), lex.uz, https://lex.uz/docs/4674902, accessed 2026-10-27
- Federal Income Tax Proclamation No. 979/2016, Ministry of Revenues of Ethiopia, https://www.mor.gov.et/DomesticProclamations/1755167125476-93265658-pdf-%C3%A1%C2%8A%C2%A0%C3%A1%C2%8B%C2%8B%C3%A1%C2%8C%C2%85-%C3%A1%C2%89%C2%81%C3%A1%C2%8C%C2%A5%C3%A1%C2%88%C2%AD-979-2008.pdf, accessed 2026-10-28
- Code Général des Impôts, édition 2021, Direction Générale des Impôts (Morocco), https://tax.gov.ma/wps/wcm/connect/30b7372b-68d0-462f-b40b-bd5c9f642a26/CGI+2021+version+fran%C3%A7aise.pdf?MOD=AJPERES&CACHEID=ROOTWORKSPACE-30b7372b-68d0-462f-b40b-bd5c9f642a26-nryAoP4, accessed 2026-10-27
- Ordonnances-lois n° 13/001 and 13/002 du 23 février 2013 (nomenclature of taxes and duties), Direction Générale des Impôts (DR Congo), https://dgi.gouv.cd/wp-content/uploads/2025/10/dgrad-code.pdf, accessed 2026-10-28
- Income Tax Act, 2015 (Act 896), sections 43 to 45, Ghana Revenue Authority, https://gra.gov.gh/wp-content/uploads/2020/09/INCOME-TAX-ACT-2015-ACT-896.pdf, accessed 2026-10-27
- Loi du pays n° 2024-34 du 10 décembre 2024 (droits d'enregistrement, article LP 79), Assemblée de la Polynésie française, https://www.assemblee.pf/travaux/downloadTexte/1727761, accessed 2026-10-28
- General Tax Law of Mongolia, article 7.2 (consolidated), Unified Legal Information System of Mongolia, https://legalinfo.mn/mn/detail?lawId=14403, accessed 2026-10-28
- Tax laws in force, Mongolian Tax Administration, https://mta.gov.mn/legal/tax, accessed 2026-10-28
- Nostos tax profiles (152 countries), Navoy, https://nostos.navoy.io/data, accessed 2026-10-28
About the Author
Haroun Moula
Haroun Moula is the founder and CEO of Navoy. Before Navoy, he worked in luxury travel with VVIPs and high-profile travelers. He built Navoy to bring curated, adaptive trip planning to more travelers through an AI travel agent that plans and books core trip parts in one place.